12 Nov 2026
European Industrials | Sector Update & Valuations by End Market
European industrial sector: valuations follow growth as end markets diverge
Our latest sector update benchmarks listed peers across ten industrial end markets, tracks how their valuations have moved over the past four years and reviews the transactions shaping European industrials M&A.
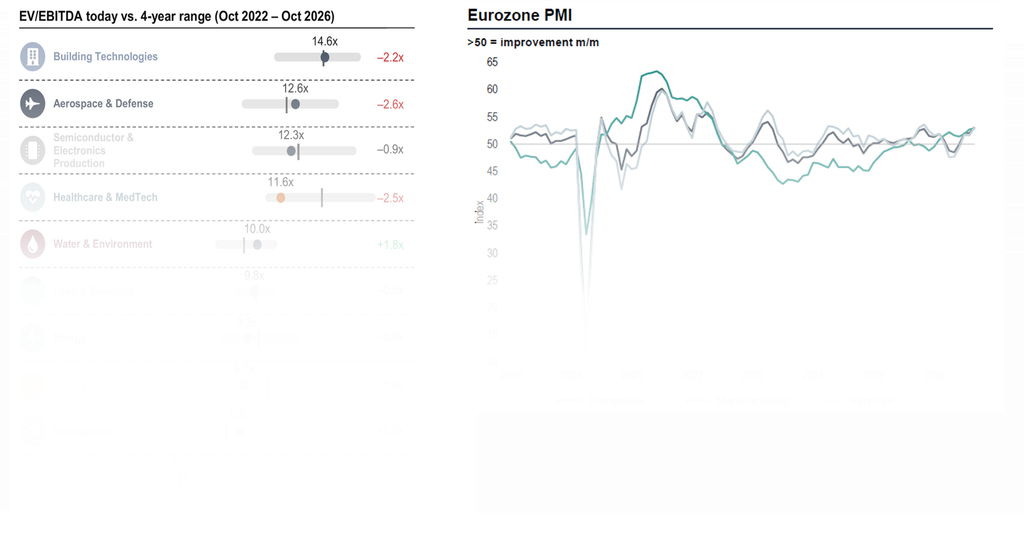
At the sector level, European industrials trade at a median 9.9x NTM EV/EBITDA, below the 10.5x four-year average and within a 9.2–11.6x range since Q1 2023. Beneath that stable median, however, multiples vary widely, from 5.0x in Automotive & Mobility to 14.6x in Building Technologies.
That stability comes against a tighter macro backdrop, with euro-area inflation back at 3.2%, Brent at $123/bbl and two ECB rate hikes this year. Even so, European industrial production is recovering, supported by rearmament, reshoring, electrification and AI-led infrastructure investment.
What the report covers:
- Macro backdrop: interest rates, inflation, energy prices and geopolitics, and how European equities are valued against the US.
- Industrial production: expected to grow 12.1% a year to 2031, driven by reshoring, electrification and automation.
- Valuations by end market: faster growth earns higher multiples, from 5.4x in Automotive & Mobility to 13.6x in Aerospace & Defense.
- Valuation trends: which end markets have re-rated, which have come off their peaks and which trade near four-year lows.
- Peer benchmarks: operating and valuation metrics for listed peers across ten end markets.
- M&A: recent deals, shaped by corporate carve-outs and investment in automation and industrial AI.
What this means for business owners and investors
A stable sector median says little about any single asset. The nearly threefold difference in valuations across end markets highlights how much a business’s sector exposure and growth prospects influence its valuation.
For owners considering a sale and buyers looking at acquisitions, positioning and timing matter. Corporates are reshaping their portfolios through carve-outs, record levels of private capital are available, and businesses linked to defense, grid, automation and building technology are attracting strategic buyers.
Contact Jens Rutten, Robert Bosch, or Matthias Odrobina to access the report and explore your M&A opportunities.