
Kick-off event on 24 September 2026
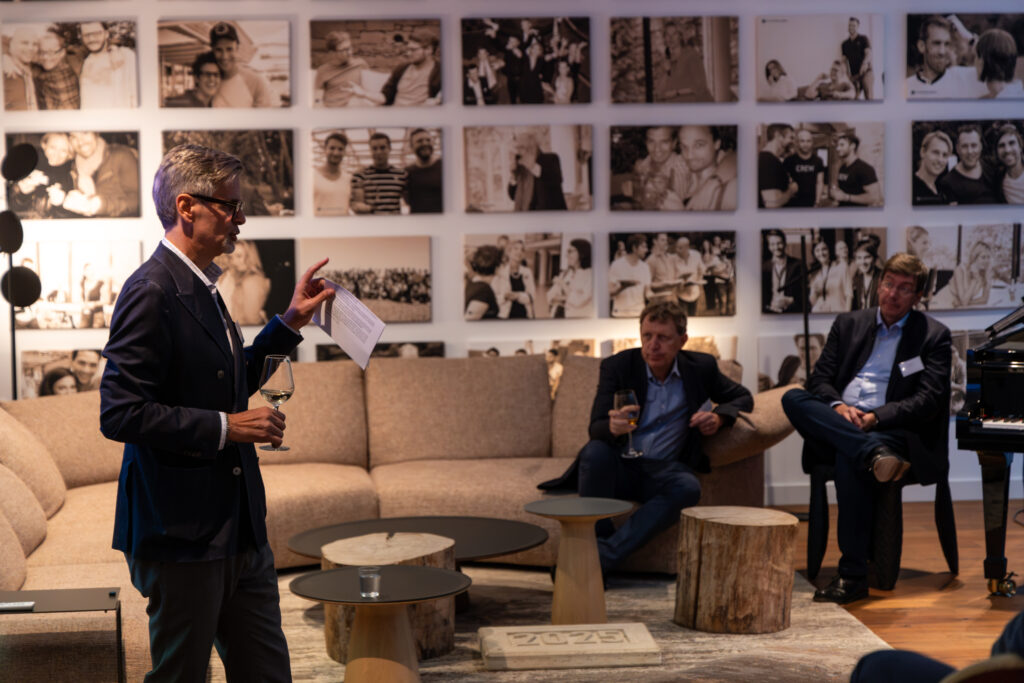
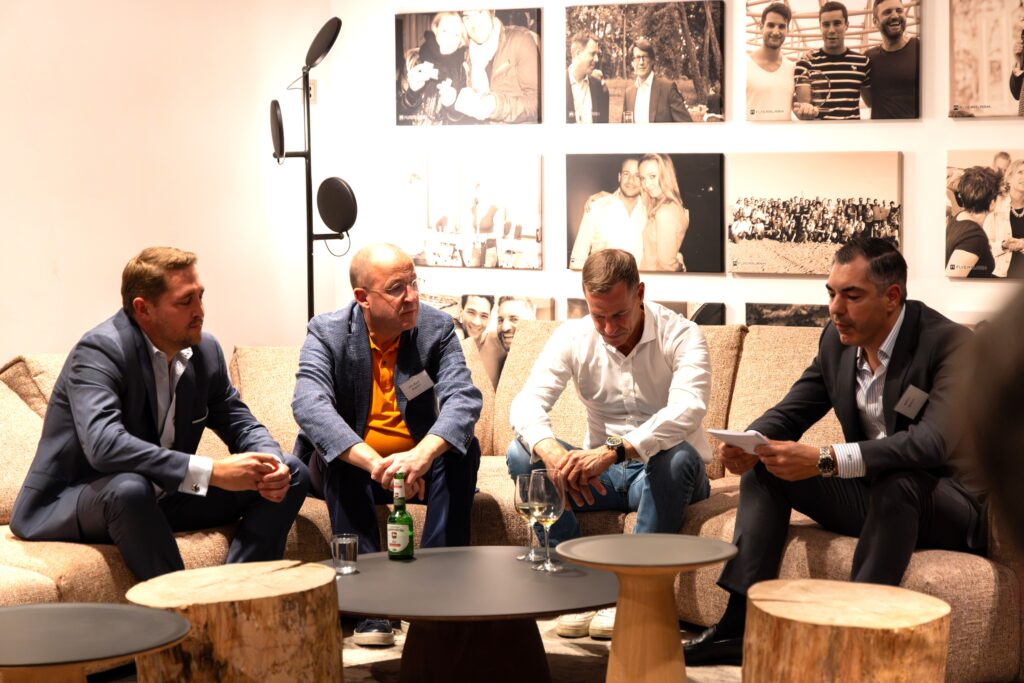
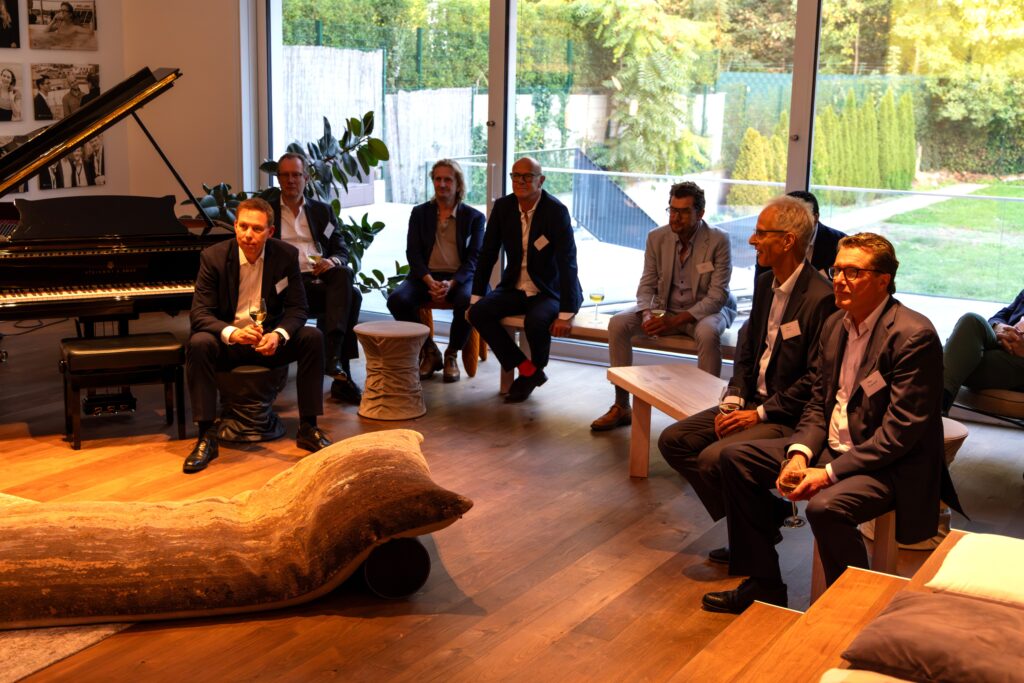
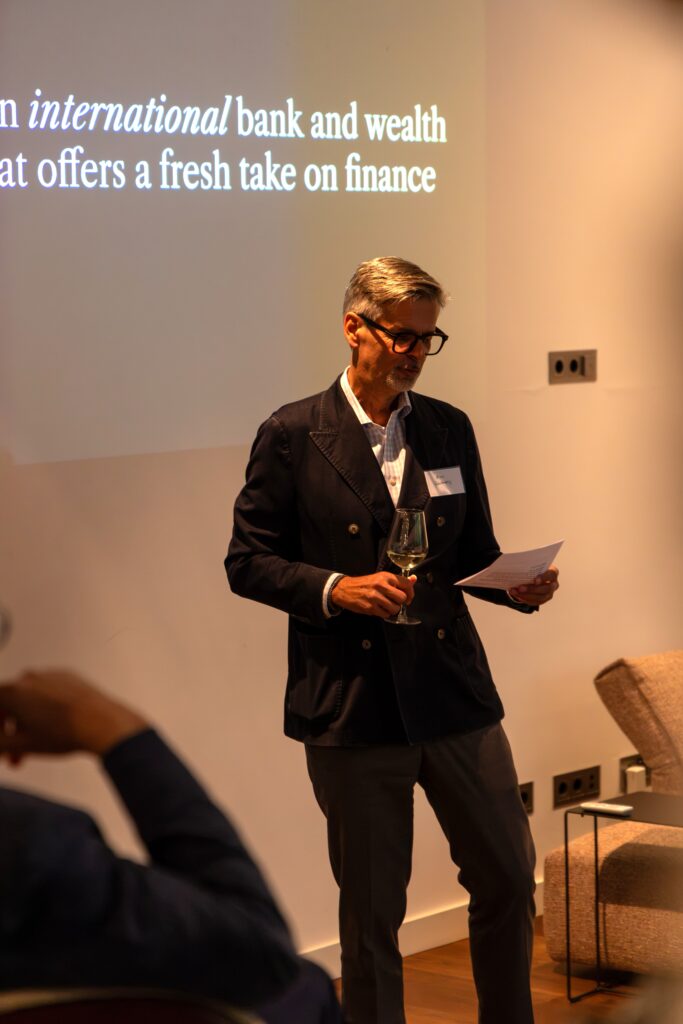
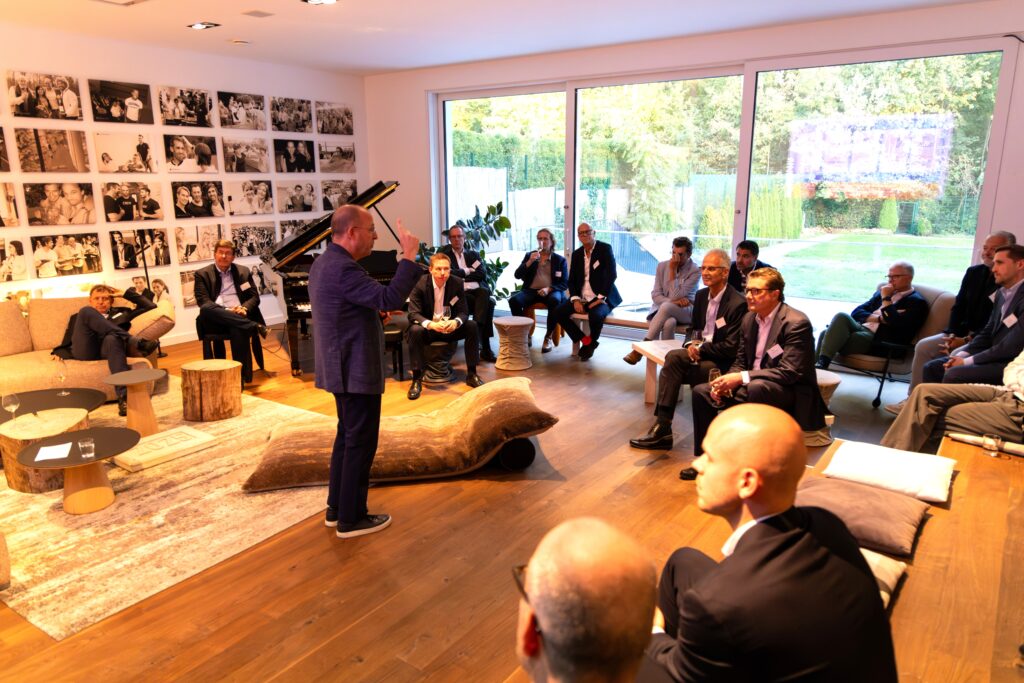
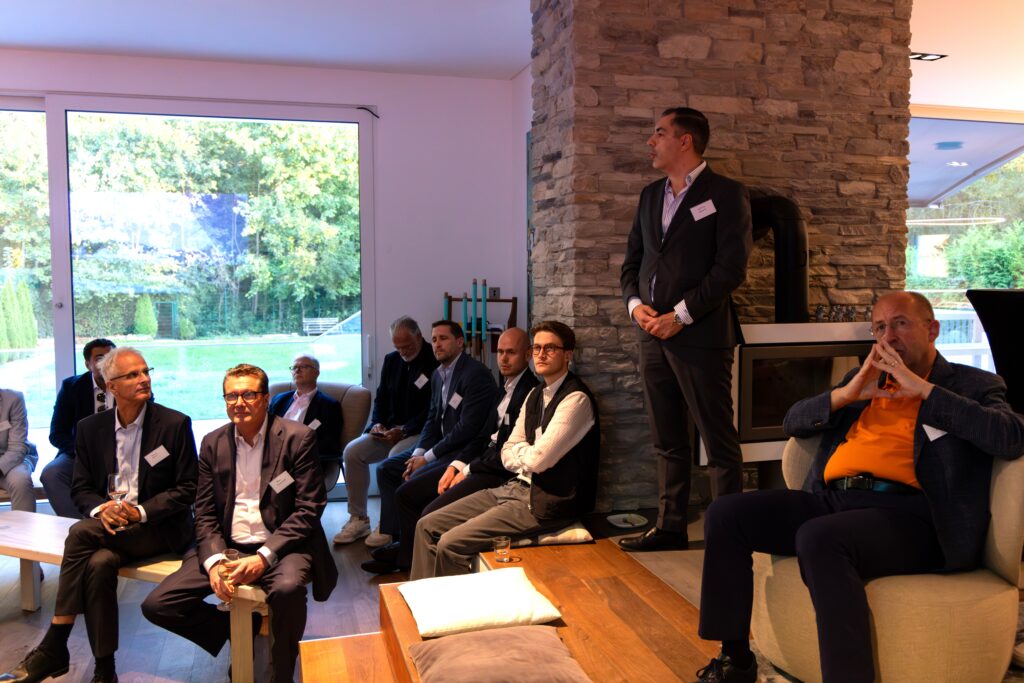
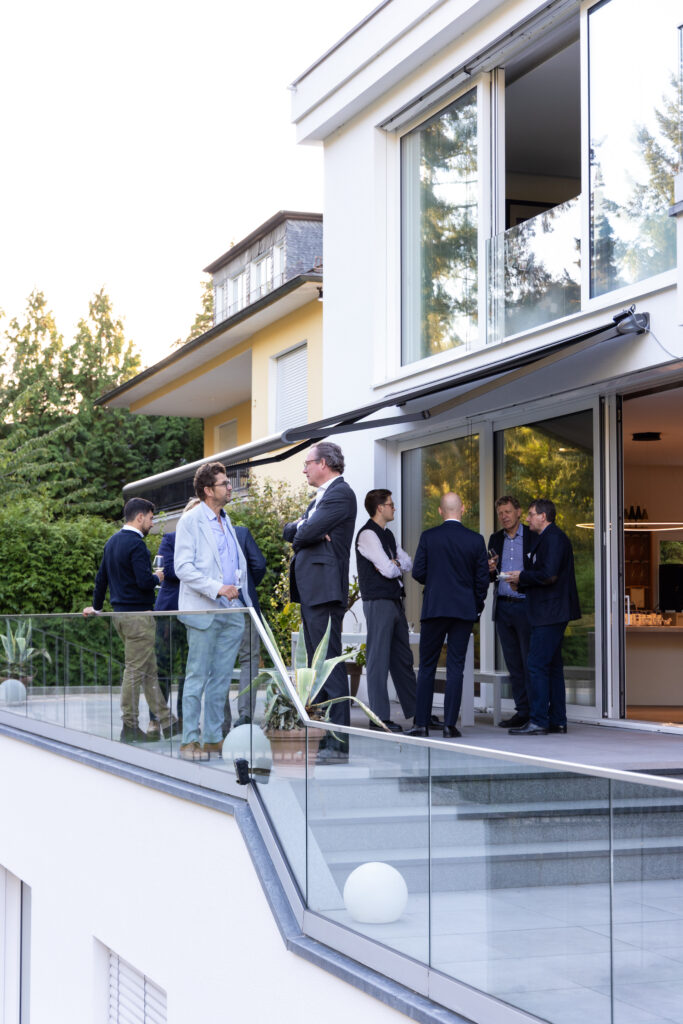
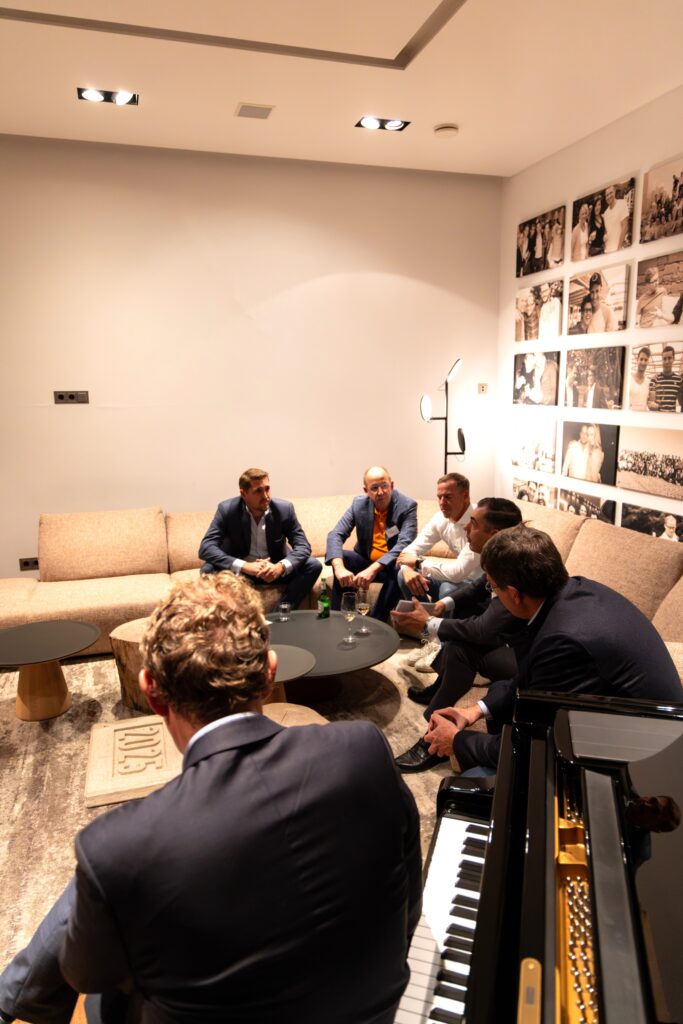
With “Makers & Shakers”, Investec Advisory aims to bring together a select group of entrepreneurs, start-up founders and C-level decision-makers from the technology, smart industrials and industrial services sectors in an engaging format. The kick-off event took place on 24 September 2026 at QX Manor in Frankfurt am Main.
Under the title “Smart Industrials: Successfully Navigating Strategic Transformation”, around 30 guests discussed how industrial convergence can be strategically shaped and what role capital allocation, M&A and in-house investments play in this process. Keynote speeches by Christoph Ritzkat (CEO, Kieback&Peter) and Dr Andreas Widl (CEO, SAMSON AG) provided the framework for the discussion, complemented by the perspective of Philipp Unterhalt (CEO, Skillaris). Matthias Odrobina (Managing Director, Investec Advisory Germany) hosted the evening.
The evening was deliberately designed to encourage dialogue: rather than a conference programme, it featured peer-to-peer exchanges amongst decision-makers facing similar strategic choices.
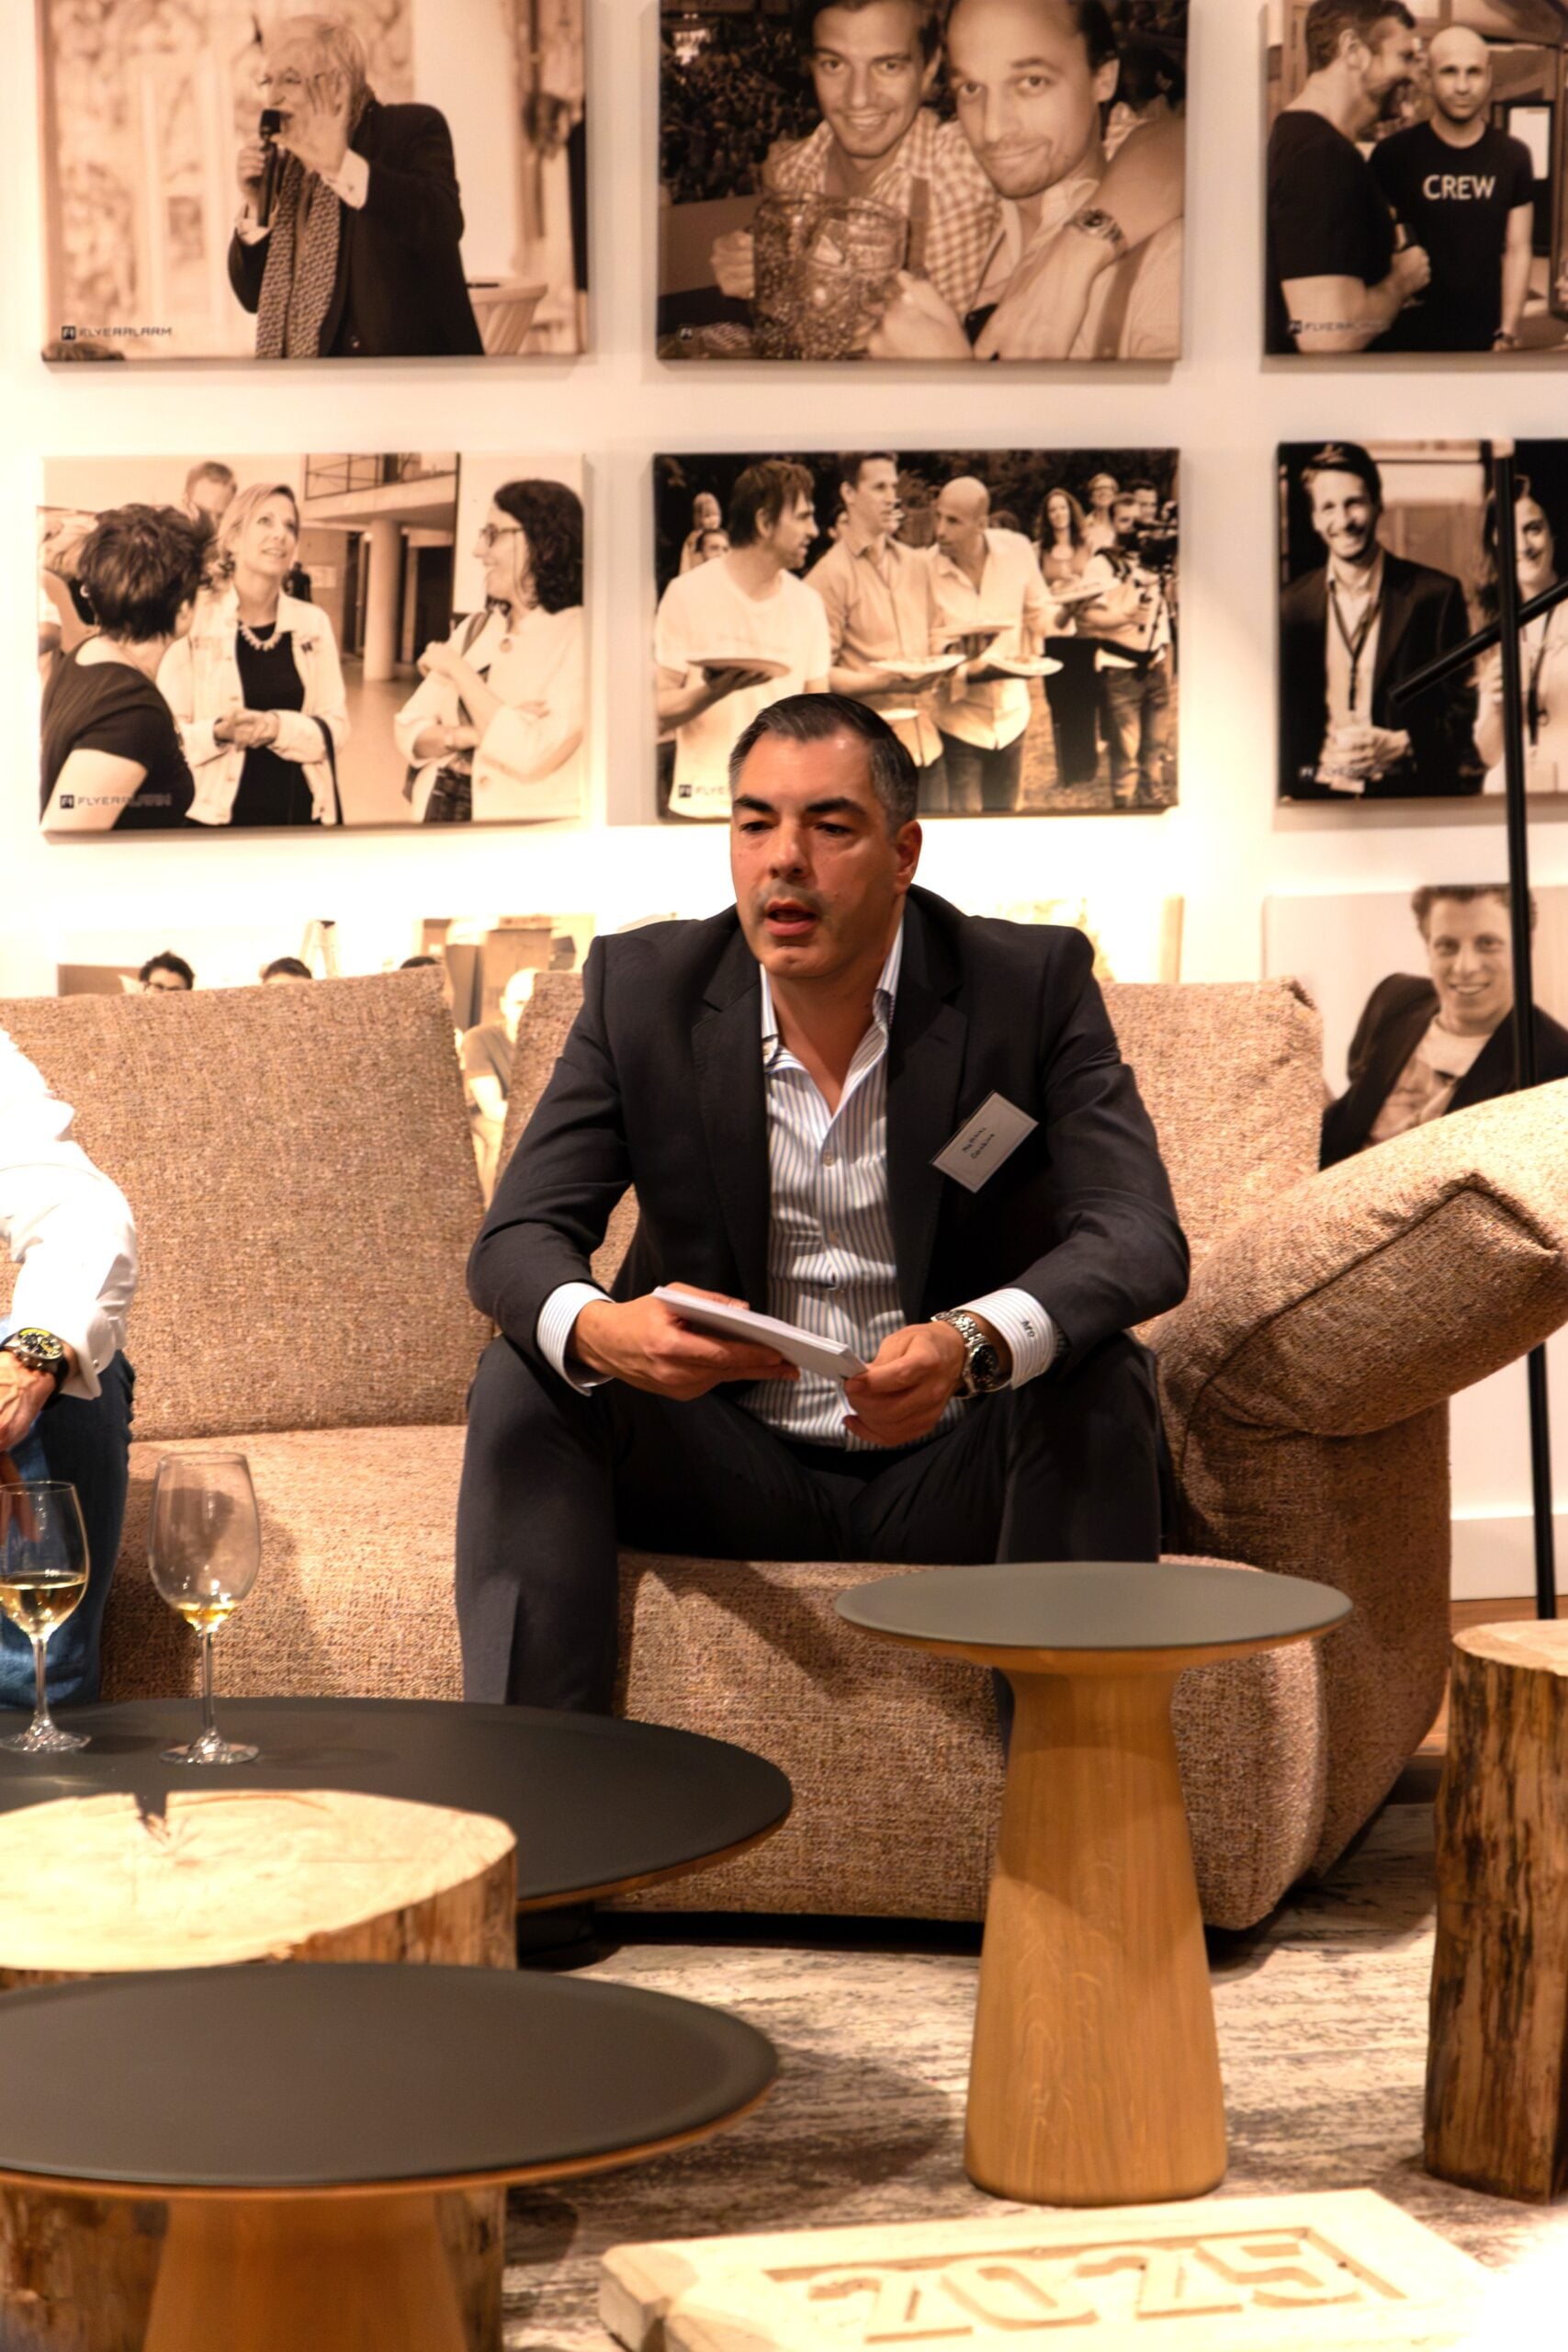
“”We are already looking forward to the next instalment of Makers & Shakers and intend to expand the series of events selectively. The participants at the launch event form the core of this community of doers who are actively shaping industrial convergence and the industry’s future viability.
– Matthias Odrobina, Managing Director Investec Advisory Germany
Event gallery
What is Sale & Lease Back financing?
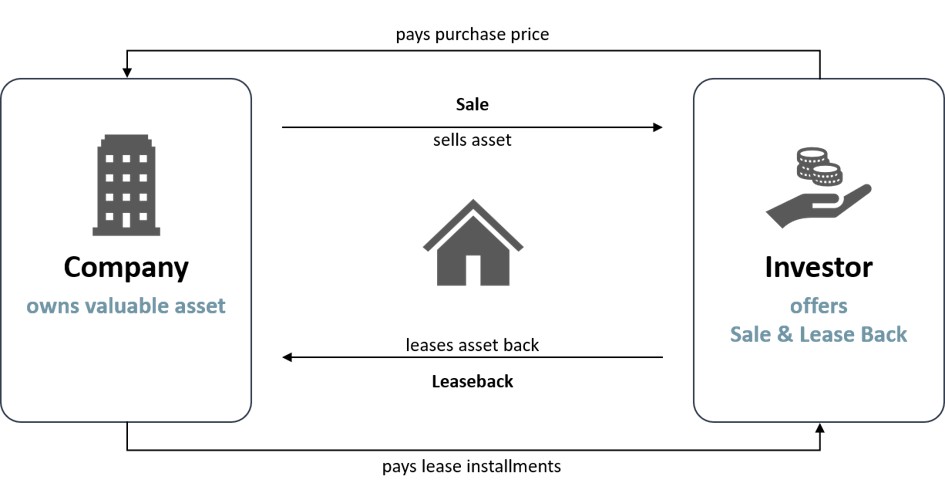
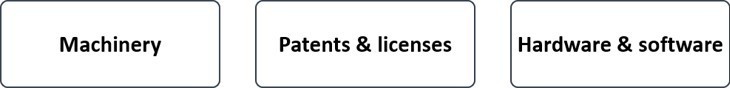
In a Sale & Lease Back (SLB), a company sells an asset to an investor and immediately leases it back on a long-term basis. In practice, these are usually business-critical properties such as plants, production facilities or warehouses, although other long-lived assets such as machinery and equipment can also be suitable. The sale proceeds flow to the company as liquidity and can be used, for example, to invest in the core business or to pay down debt. In return, the company pays regular rent and continues to use the property as before. The lease term, renewal and buyback options, and the allocation of maintenance, taxes and insurance are negotiated individually between the parties. An SLB is not an instrument reserved for special situations, but a standard component of the financing mix, alongside traditional instruments such as bank loans and equity.
What are the advantages of Sale & Lease Back financing?
- Market value instead of lending limits: Banks only lend against part of a property’s value, leaving the company to fund the rest with equity. In an SLB, the purchase price is based on the full market value. An SLB replaces not only debt but also equity tied up in the property.
- Business as usual: The company continues to use the property; its location and operations remain unaffected.
- Predictability without refinancing risk: Instead of a loan with a fixed-rate period that eventually needs refinancing, the company has a long-term lease.
- Fewer restrictions: Financial covenants found in loan agreements are uncommon in leases. Like banks, however, investors usually require rent deposits or guarantees and regular financial reporting.
- Additional source of financing: An SLB complements bank financing and preserves existing credit lines.
Why is Sale & Lease Back particularly relevant right now?
Banks are becoming increasingly cautious: according to the Bundesbank’s Bank Lending Survey, banks tightened their credit standards for corporate loans again in the second quarter of 2026. Companies are feeling the impact: in the same period, 40.5% of SMEs in need of credit described their banks as restrictive, the highest share since the KfW-ifo survey began in 2017. Among large companies, the figure was 32.9%, the second-highest level on record. At the same time, investment needs are high: according to the BDI study “Transformation Paths”, Germany will require around €1.4 trillion in additional investment by 2030, roughly two-thirds of it from companies and private households.
On top of this, many SMEs are facing a generational handover: according to KfW, around 545,000 small and medium-sized companies are seeking a succession solution by the end of 2029, which amounts to just over 109,000 per year. Operational real estate often complicate the handover, for example when the operating business is to be transferred but the property is not.
Meanwhile, companies looking to sell are meeting a market that is picking up again: according to JLL, investment volume in German logistics and industrial real estate rose by 22% to €2.9 billion in the first half of 2026, significantly outpacing the overall market (+15%).
Why is operational real estate well suited to a Sale & Lease Back?
Operational real estate often hold considerably more value than the balance sheet suggests: they are carried at historical cost and depreciated on a scheduled basis, while their market value has often increased over the years. At the same time, owning the property ties up capital for decades. This capital is then unavailable for the core business, for example for machinery, automation or research and development. An SLB turns these hidden reserves into usable liquidity.
SLB investors also approach their investment decisions differently from banks. Whereas banks assess the company’s overall situation on the basis of a rating, investors focus primarily on the property (i.e., location, alternative-use potential and condition), the term of the SLB and the tenant’s ability to meet the lease payments. This creates additional financing headroom, independent of existing credit lines.
SLB structures once again dominated property sales by German companies in 2025, with the share accounted for by manufacturing companies rising from 25% (2015 to 2019) to 46%. Across Europe, too, the majority of SLB transactions involve industrial properties.
Which other assets are best suited to a Sale & Lease Back?
When is Sale & Lease Back financing an option for your company?
- To finance investments, transformation and expansion
- To finance an acquisition
- To repay or refinance existing loans
- As part of a business succession or a change of shareholders
- In preparation for a sale of the company
- When selling a business unit (carve-out)
- For general liquidity management
Have we sparked your interest, or do you have any questions? We would be pleased to assess with you, in strict confidence, in which situations a Sale & Lease Back can support your business. We always consider an SLB in comparison with other financing options such as bank loans or equity, as depending on the starting position, an SLB can offer significant advantages, for example in terms of the achievable financing volume or the restrictions involved. We advise on SLB transactions from around €10 million, from the initial assessment through to closing.
Your contacts
Thorsten Gladiator and Gaurav Kapoor
The Dutch technical services market is worth approximately €20bn. Our sector team’s latest report looks at why it is growing, and where the opportunity sits for buyers and operators.
What the report covers:
- a market recovering to growth through 2027, after a dip in 2023 and 2024
- demand underpinned by regulation, including the affordable rent act (Wet betaalbare huur) and national housing targets, making a large share of work non-discretionary
- a highly fragmented market: the top 10 companies hold 23% of it, yet represent about 1% of the roughly 5,300 companies active in it
- an active M&A market: 15 or more PE-backed platforms compete for assets, with approximately 85 Benelux targets changing hands in the last two and a half years
- platform-quality assets trade at 8 to 12x EBITDA; listed technical services peers average 12.1x EV/EBITDA, above the five-year average of 10.9x
- climate (HVAC) as the fastest-growing domain, with residential the leading end-market
To request the full report, contact Robert Bosch or Jasper Erhardt.
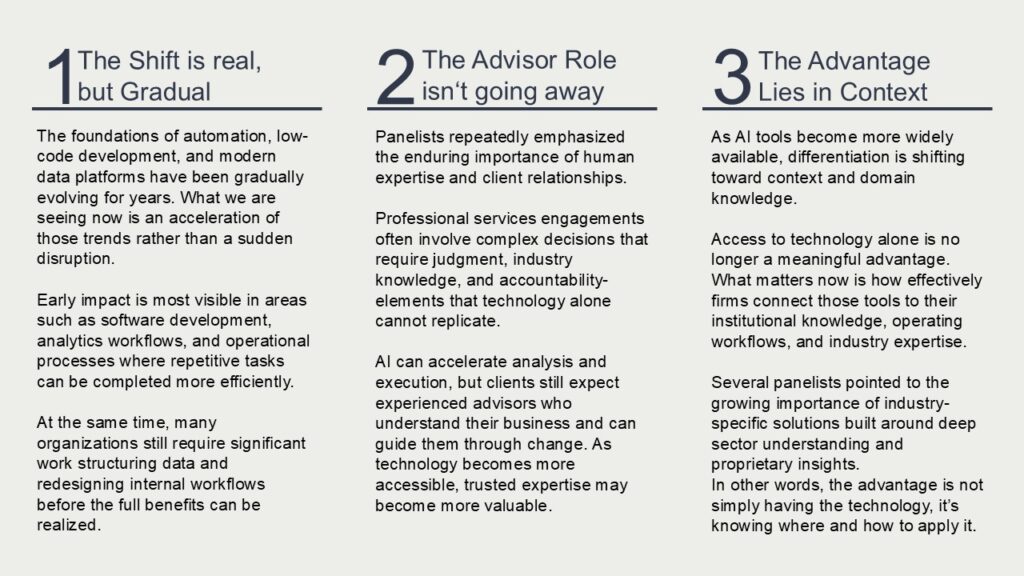
Five key themes have emerged from Clearsight´s Conference and our recent Professional Services & Consulting roadshow within Germany.
At this year‘s Knowledge Economy Summit hosted by our US partner Clearsight,a panel of industry leaders discussed a question increasingly raised across boardrooms and deal processes:
How will artificial intelligence impact the future of professional and tech-enabled services businesses?
Rather than focusing on headlines, the panel explored the practical implications for how services firms build teams, deliver work, and compete. Participants included:
- Stuart Ferguson, President, Pointe Advisory now part of Stout (Moderator)
- Will Hayllar, Global Managing Partner, O C & C Strategy Consulting
- Sanjaykumar Joshi, Global Lead-Data Management, EXLServices
- Nir Kaldero, Chief Data & AI Strategist, EPAM
- Yuriy Yuzifovich, CTO-AI, Global Logic
Explore five key takeways from the discussion below.
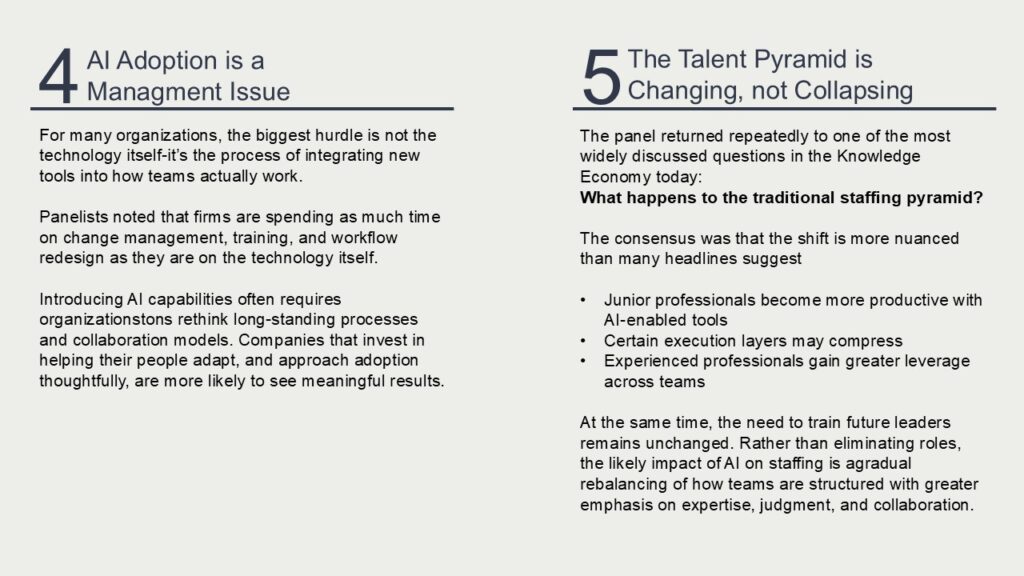
The challenge ahead is designing new apprenticeship models that prepare the next generation of advisors while incorporating technology into how work is delivered.
If you have questions and would like to know more – please get in touch: ervin.schellenberg@investec.com, mirko.nikkels@investec.com
Strengthening our Industrial Tech & Services team
Investec is pleased to welcome Matthias Odrobina as Managing Director of our European Business Advisory and a senior member of the global sector team covering Europe, UK, Africa, the US and Asia with impartial advice on cross-border transactions.
Matthias brings deep sector expertise across industrial technology (particular focus on smart industries, B2B software and digital transformation).
He has 20 years of experience as a trusted partner to boards and owners on mergers, acquisitions, divestitures, financings, and buyouts, with a particular focus on the industrial sector, B2B software, and business services.
Contact: Matthias Odrobina
Sector multiples have reset above the long-term median – but the index average masks the real story.
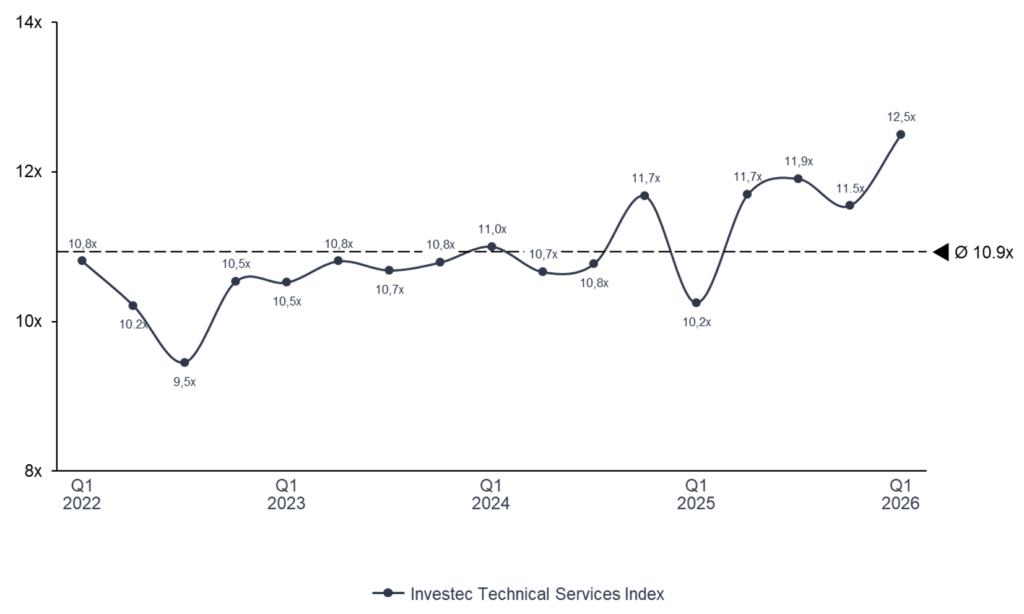
The Technical Services Index is trading at 12.5x EV/EBITDA in Q1 2026, +1.6x above the long-term average of 10.9x and +2.3x above Q1 2025.
Investors are no longer pricing technical services as a single cyclical block. After three years of selective re-rating, the market has unbundled the index into four distinctly priced narratives – power, project execution, recurring service quality, and engineering scarcity – andthe spread between them is at its widest of the cycle.
Resilient deal volumes (67 European transactions in Q1) and a step-up in cross-border participation (40%, vs. low-30s through 2025) confirm that buyer appetite remains intact, but selectivity has sharpened materially.
What’s behind the re-rating
The index has rebuilt steadily since the Q4 2022 reset, but the path has not been linear. Multiples held in a narrow band through 2023–24 as investors worked through the rate-shock repricing, then accelerated through 2025 as backlog visibility, energy-transition capex and the AI infrastructure build-out translated into earnings upgrades – not just multiple expansion. The current premium to long-term mean is being underwritten by delivered earnings, not narrative. That distinction matters for what comes next.
The market is rewarding service models that combine recurring revenues, mission-critical exposure and demonstrable margin expansion – and applying a clear discount everywhere else.
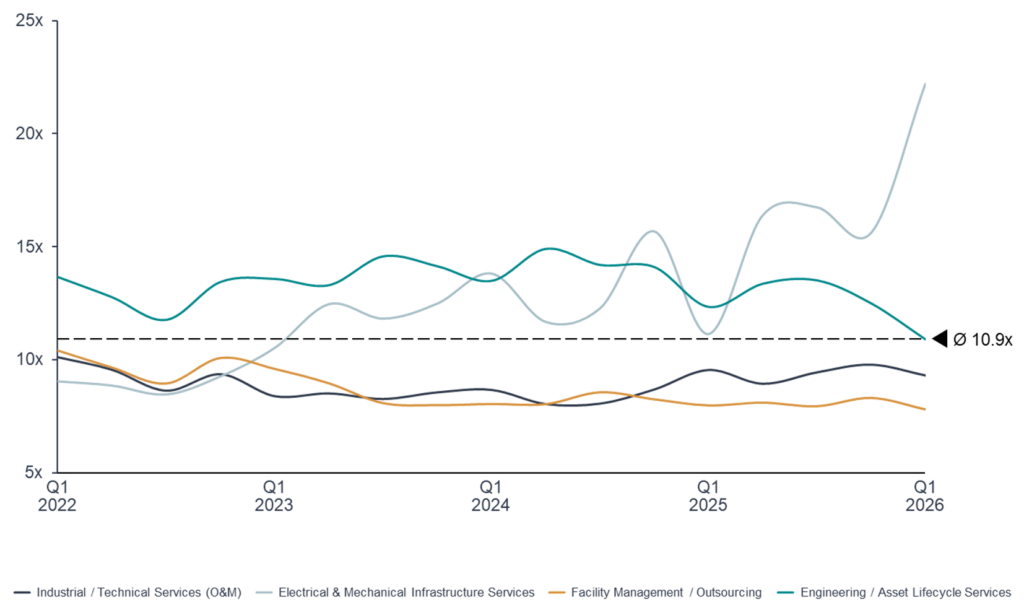
EV/EBITDA: Segment comparison Q1 2022 – Q1 2026
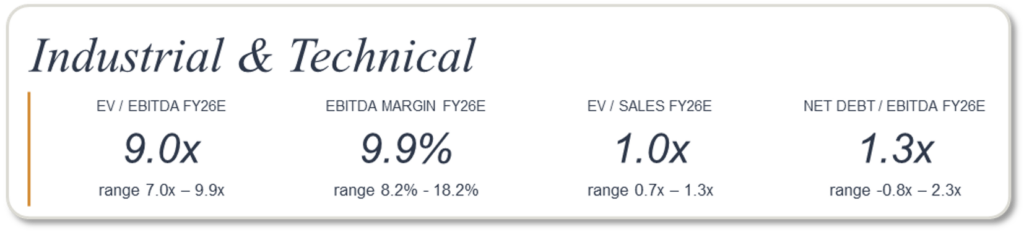
The segment trades broadly in line with the index, supported by a clear and increasingly consistent strategic playbook across the leading platforms.
- Margin ambition has reset structurally upwards across the multi-technical platforms – medium-term EBITA targets now cluster in the 8–9% range, a step-up from the 6–7% delivered through the prior cycle, and forward 2027E multiples already compress to ~8.6x as the market underwrites delivery
- Portfolio repositioning toward energy transition, data centre and pharma end-markets is a segment-wide strategic priority, replacing legacy oil & gas and general industrial exposure
- Bolt-on M&A remains the primary growth engine – leading platforms are deploying capital at a pace materially above prior cycles, supplied by a still-fragmented European mid-market
- Pricing power has shifted to providers as labour scarcity in skilled trades has changed the negotiating dynamic on outsourced industrial maintenance contracts
- Mission-critical backlog mix is rising – multi-technical service contracts are increasingly anchored in regulated, safety-critical infrastructure, lifting the recurring component of revenue
Investors are paying for delivery on stated margin paths and continued M&A optionality. Tolerance for execution slippage is limited.
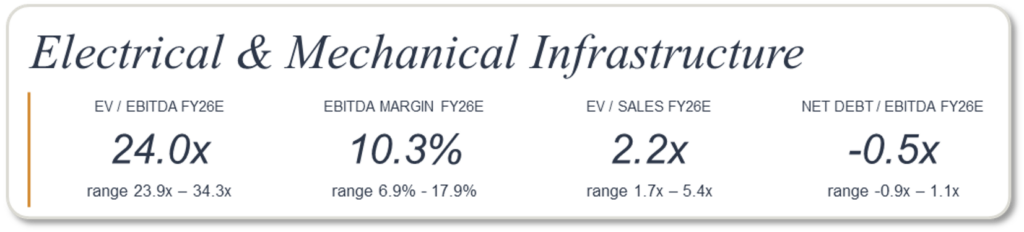
The standout segment of the cycle, with a valuation premium of ~16 turns versus Facility Management – pricing structural exposure to the most concentrated capex super-cycle in industrial services.
- Combined backlogs across the cohort have grown +34% year-on-year, with hyperscaler-driven data centre work the fastest-growing pocket and electric grid build-out providing a multi-year secondary leg
- Customer mix has pivoted decisively toward technology buyers across the cohort – hyperscaler and data-centre work is now a meaningful share of new awards across the cohort, with the most exposed names having moved from a structurally limited share of revenue to majority technology exposure inside two years
- Capacity expansion is the segment’s strategic priority – both physical capacity and contracted labour pools through master service agreements are being scaled materially across the cohort to convert record backlogs
- Selective M&A in specialty electrical and mechanical adjacencies is reinforcing premium positioning rather than diluting margin
- Margins are at or near cycle peaks and balance sheets are increasingly net cash, providing optionality without near-term re-leveraging risk
The risk is asymmetric: 24.0x embeds a multi-year continuation of current capex trajectories. Historical analogues from prior pauses suggest 30–50% multiple compression within weeks of any confirmed inflection. Investors are paying for backlog duration, not cycle-stage normalisation.
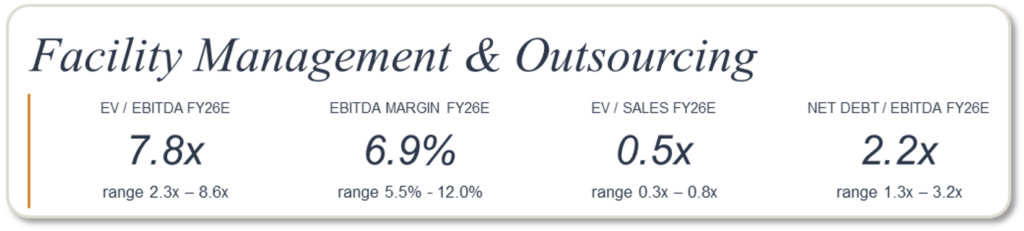
The structural laggard of the index – but the discount is becoming differentiated, and that bifurcation is the more important development.
- The segment-level discount reflects genuine fundamentals – lowest aggregate growth (4.8% in 2025/26), thinnest margins (6.9%) and highest leverage (2.2x net debt/EBITDA)
- Mix shift away from manned services toward technology-enabled and compliance offerings is the defining strategic playbook for the leaders
- Balance-sheet discipline through systematic capital return – sustained buyback programmes and progressive dividends – is increasingly part of the equity story
- Selective M&A in higher-margin adjacencies is repricing the leaders – security technology, integrated workplace technology, compliance and TIC services have transacted at multiples well into the teens
- Evidence of strategic delivery is accumulating at the leading end of the segment – long-stated medium-term margin targets are being hit, technology mix is now meaningfully contributing to profit pools, and contract pipelines have expanded materially through the most recent reporting cycle
- The laggards have validated the discount – material guidance downgrades among segment incumbents, including organic growth resets to near-flat and margin reductions of more than 100 basis points within a single fiscal year, reinforce the case for selectivity
Buyers are paying up for technology mix and recurring contract quality. Pure manned-services exposure remains comprehensively discounted.
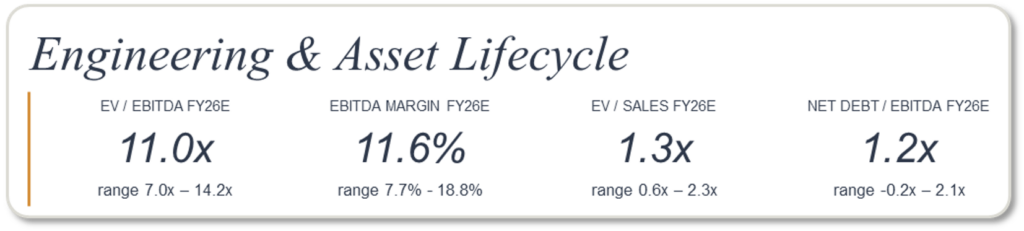
The most strategically coherent segment in the index, and the one where M&A is most actively reshaping the peer set.
- Three converging structural advantages underpin the premium – highest aggregate margins in the index (11.6% segment median FY26 EBITDA, with the upper quartile delivering 17–18%), multi-year backlog visibility through long-cycle programmes, and direct exposure to scarce specialist verticals
- Scarce-vertical exposure is the primary valuation driver – nuclear new-build and refurbishment, water infrastructure, grid and energy transition, and defence
- Strategic acquirers are paying materially for energy positioning – recent transactions in energy-transition consulting have priced at 14–15x pre-synergy EBITDA, well above the wider segment average
- A margin-convergence story is playing out across the leading end of the segment – platforms with publicly stated medium-term Adjusted EBITDA targets in the 17–20% range are now at or within 100 bps of those targets
- Capital allocation is broadening from M&A-only toward buybacks as platforms approach their margin targets, signalling cycle maturity at the leading end
Premium pricing of scarce specialist capability and disciplined margin convergence at the leaders will drive most of the stock selection within Engineering through 2026.
M&A activity – selectivity, scale, and the rise of cross-border
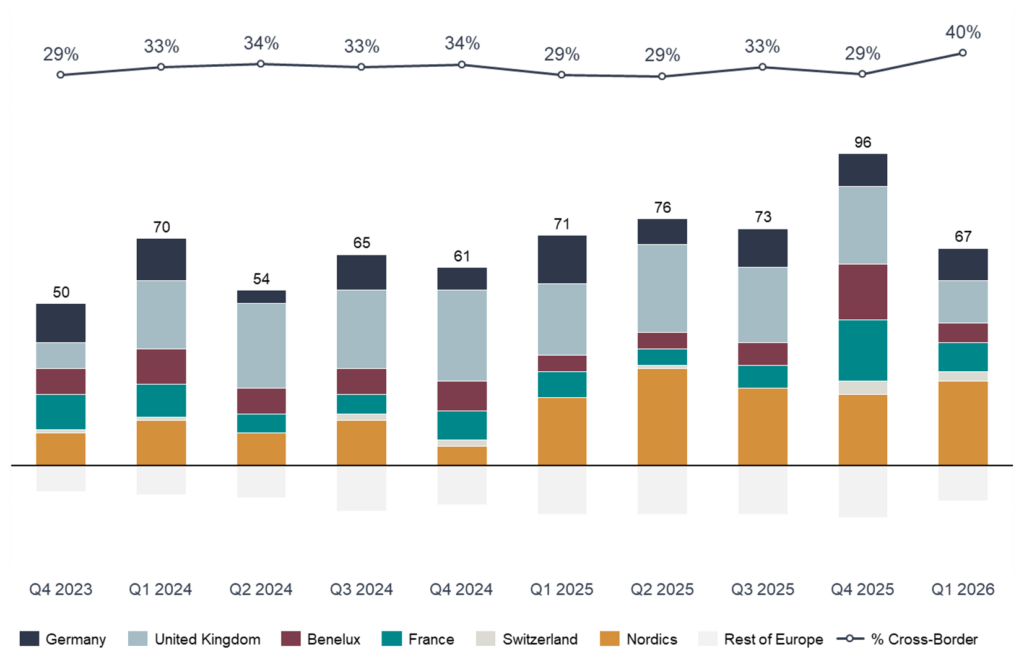
Q1 2026 confirmed two of our central theses on the European deal market. First, transaction volumes have remained resilient at 67 deals – broadly in line with the four-quarter average – despite higher financing costs, indicating that strategic and sponsor capital deployment is now structurally embedded rather than cycle-dependent. Second, and more importantly, cross-border participation rose to 40%, materially above the c.33% trailing pattern of the past two years.
The cross-border step-up reflects two reinforcing dynamics. Strategic acquirers – particularly those repositioning toward power, energy transition and nuclear – are reaching across borders to acquire specialist capability that cannot be built organically at the required pace. Sponsors, in parallel, are increasingly comfortable underwriting multi-jurisdictional roll-up theses where local-champion platforms can be combined into pan-European leaders. Recent benchmark transactions in the period – including a $3.3bn engineering acquisition disclosed at 14.5x pre-synergy EBITDA and a c.€4bn sponsor recapitalisation in European facility management at an estimated 12–13x – confirm both the depth of capital available and the multiples that scale platform assets continue to command.
For owners, this matters concretely: competitive tension in well-run sale processes is increasing, and the buyer universe for premium assets is materially larger today than in any year since 2021.
Investors reward profitable growth
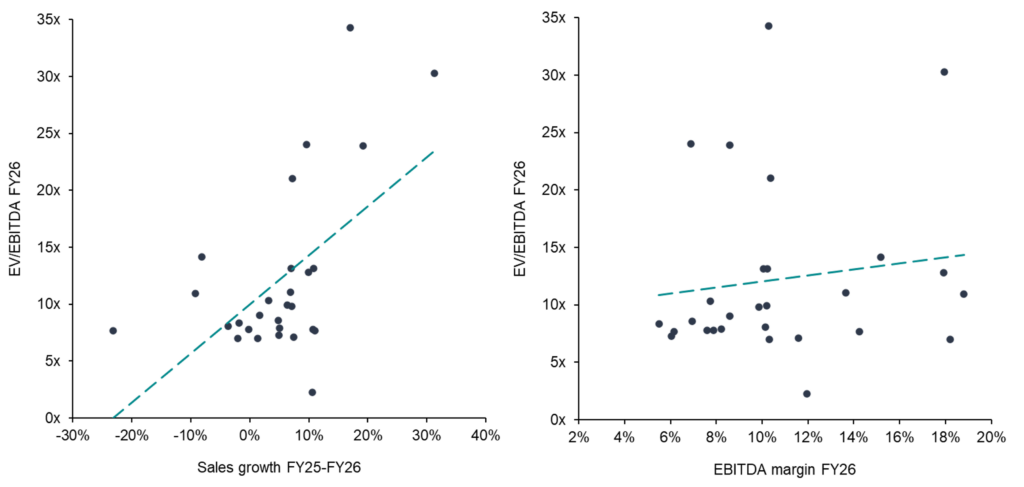
The two charts make the underwriting model of today’s market explicit. Forward sales growth tracks tightly with FY26 trading multiples – each percentage point of expected growth corresponds to roughly half a turn of EV/EBITDA – while FY26 EBITDA margin shows no meaningful relationship at all. Read together, the pattern confirms what the segment commentary has set out: the market is paying for visible, contracted growth, with margin acting as the qualifier that separates underwritten growth from narrative growth, not as a primary driver in its own right.
What this means for owners and investors
For entrepreneurs, the message is sharper than at any point in the past three cycles. Premium valuation outcomes are increasingly driven by recurring revenues, demonstrable margin resilience, and the ability to articulate strategic relevance within a defined value chain – not by aggregate growth. Top-line CAGR alone no longer commands a premium. Buyers are dissecting revenue mix, contract duration, and end-market exposure with substantially more discipline than they applied during the 2021 peak.
For investors and strategics, selectivity is paramount. Scaled platforms with clear consolidation theses, recurring service exposure, and defensible end-market positions continue to attract the deepest pools of capital and the highest exit multiples. Generic exposure – to construction cyclicality, to manned-only services, to government-revenue concentration, to mid-cycle margin levels – is being systematically discounted.
In today’s market, valuation premiums are not driven by growth in isolation. They are driven by visibility, resilience and strategic scarcity – and the index dispersion at the close of Q1 2026 is the clearest evidence yet that buyers are pricing accordingly.
The Investec Technical Service Index tracks daily developments across the technical services landscape, covering sectors such as Maintenance & Repair, Installation & Commissioning, Engineering Services, Asset Management and Field Services. The index includes valuations, growth projections, profitability margins and other key metrics. You can find more information on our website and specific industry insights in our latest Industrial Services Report.
Investec has a senior team in Technical Services, who are experienced experts in selling, buying, and financing businesses. If you have questions and would like to know more about valuations, buyer activity and current opportunities in the market – please get in touch: ervin.schellenberg@investec.com, arne.laarveld@investec.com, matthias.odrobina@investec.com, yves.scharf@investec.com, julius.kreutz@investec.com
What needs to be considered?
SUCCESS FACTORS
Plan your succession
Succession is one of the most important decisions in the life of an entrepreneur. It requires time, careful preparation and a clear plan.
The handover plan
Define clear goals: measure the extent to which you are financially and mentally ready for the exit and develop an understanding of the value of the chosen succession option.
A transferable company
Create a business model that works without you. This way you will find the best buyer and achieve the highest valuation.
Advisor
Choose advisors with industry expertise who have access to potential buyers worldwide and can implement all transaction options.
Prepare yourself! No success without preparation
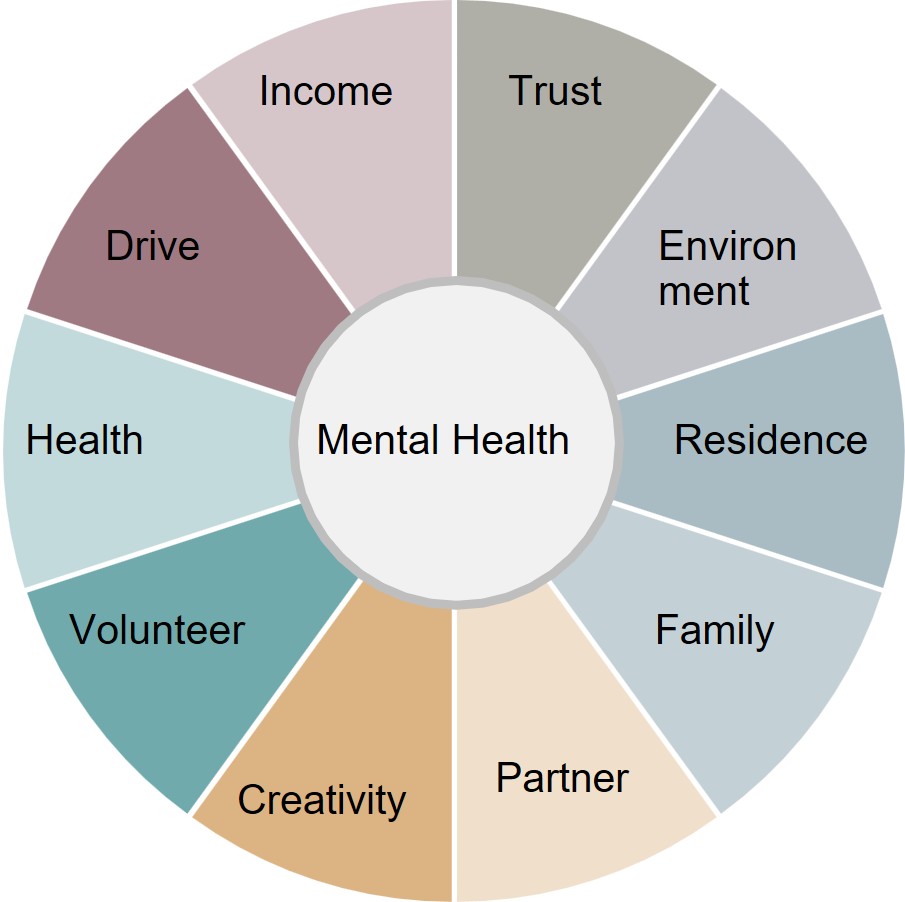
PERSONAL READINESS?
Some entrepreneurs want to continue working in the company, others don’t. How involved are you in the day-to-day business? How do you want to spend your free time after you leave? Can you let go?
Which interests are particularly important to you?
- Continued existence as an independent company
- Long-term and sustainable solution, especially with regard to a secure future for employees
- Financing necessary investments in technology, process efficiency, etc.
- Securing the company’s own asset position and realising the true value of the company
- Handing over the life’s work
- Supply security for family members
- Preservation of reputation as a good owner after the sale
FINANCIAL STATUS?
Entrepreneurs often have a lot of net assets tied up in the company and also like to overestimate the value of their own life’s work. Here it is not always easy, but it always makes sense to be objective.
Diversify your assets, create liquidity
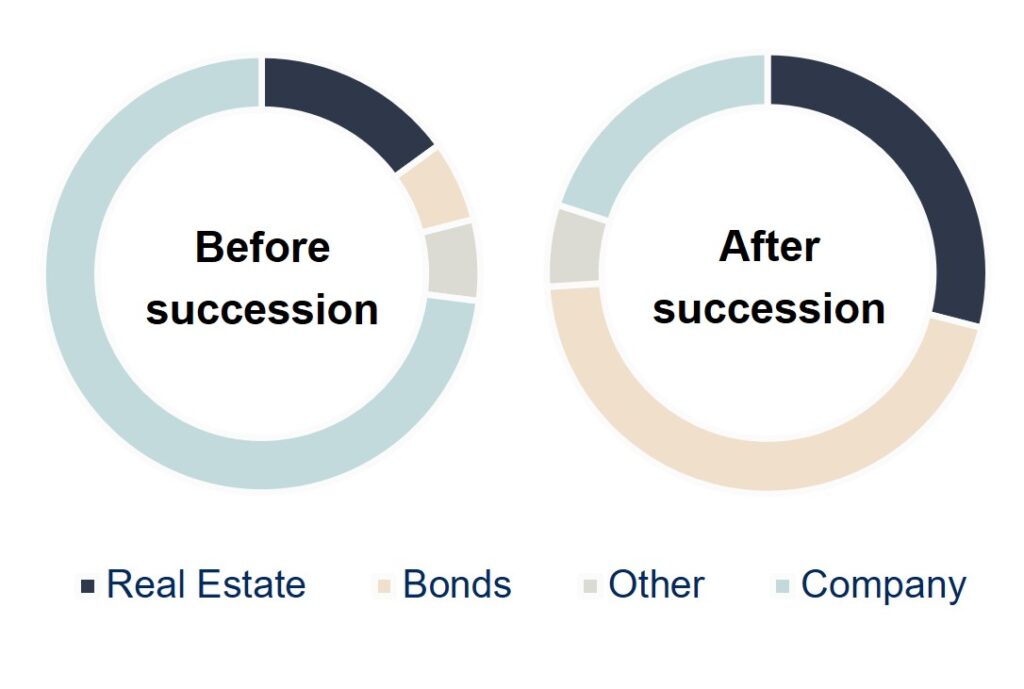
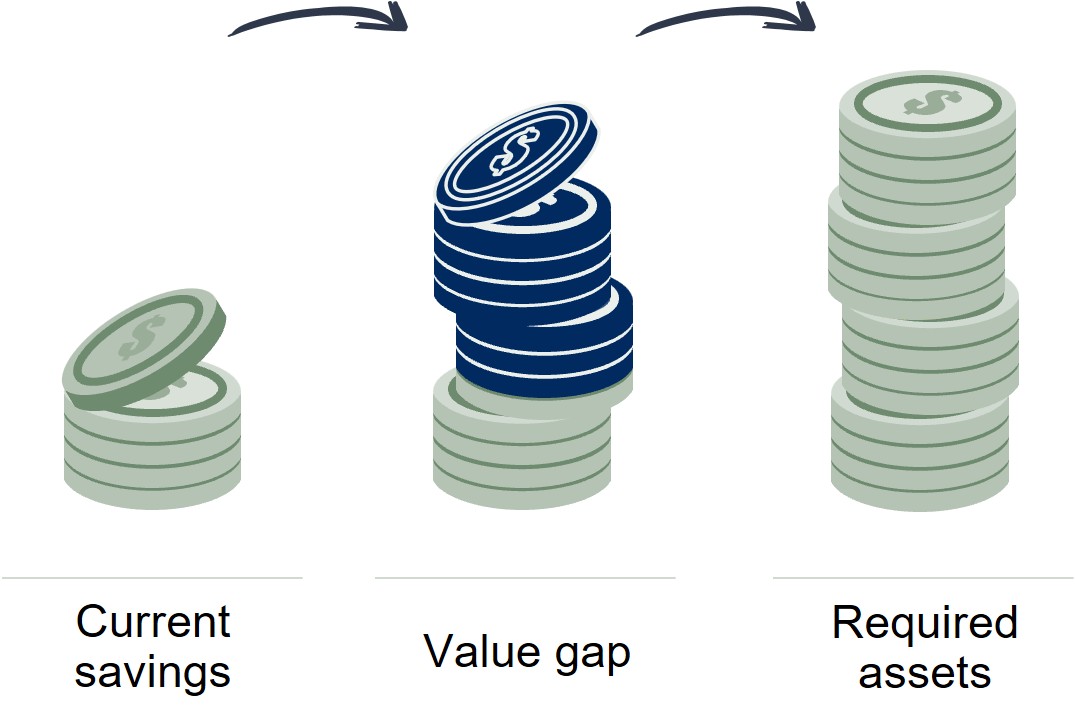
We observe that the value of an active entrepreneur’s own company often corresponds to over 70 percent of his total assets. Other defenses such as shareholder loans, personal liabilities for company loans and rental income from real estate are additionally observable. The lack of diversification, liquidity and dependence on one’s own labour and health represent a risk to be considered with increasing age.
See value gaps in good time
Is it really realistic that in the last stage of your career you create growth in your company that you never managed? Often we hear I’m restructuring sales, I have a great idea, sometimes it works. But often we see entrepreneurs who at the same time take 50 days of holiday that is well deserved, need dividends, take high salaries for lifestyle etc. That doesn’t fit with the desired increase in value. What do you want?
COMPANY TRANSFERABLE?
Medium-sized companies are often strongly influenced by their owners. They are also often the bearers of know-how, have decisive contacts to customers and suppliers and are the person of trust towards the employees. They are the contact person for all major problems.
Transferability checklist
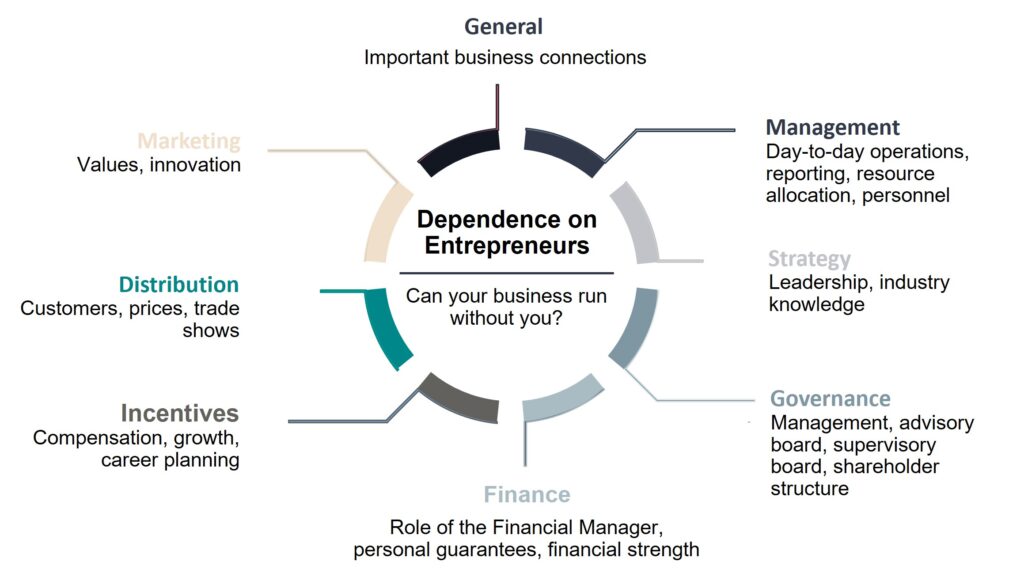
Successful successions require clarity. Often, both outside management and essential second-level functions are missing. However, it is often difficult to incentivize the right managers alone.
CHOOSE SUCCESSION SOLUTION
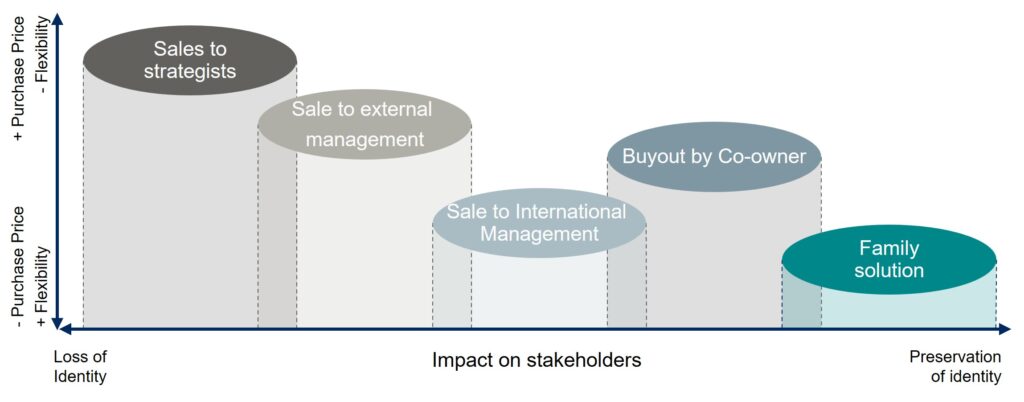
Who you transfer the company to depends on many factors that you should realistically assess before you initiate a process. It is important to do this in an unbiased way and not to follow any “beliefs”, such as the strategist is good, the financial investor is bad, and so on. All options should be considered realistically in relation to the achievement of objectives.
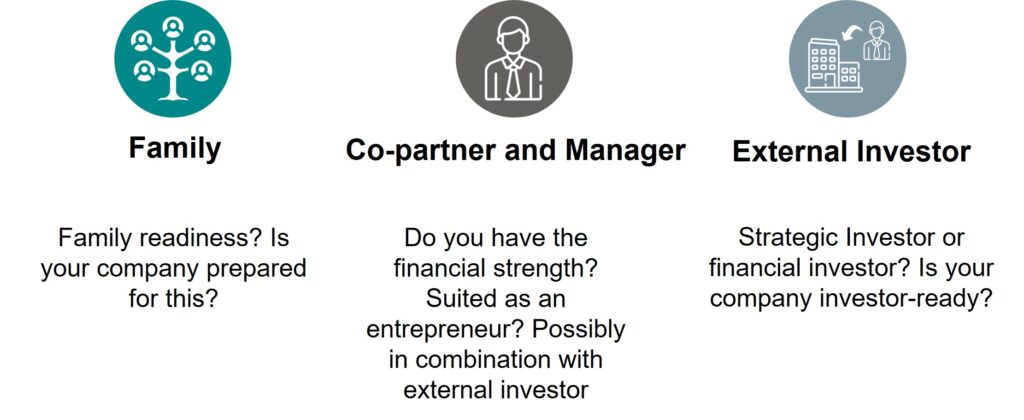
Succession solutions define various advantages and disadvantages
INVESTEC HAS MANY YEARS OF EXPERIENCE AND CUSTOMER RELATIONSHIPS
Would you like to learn more? Please feel free to contact us.
Ervin Schellenberg, Managing Partner: ervin.schellenberg@investec.com
Changing dynamics are supporting conditions for outperformance in the Testing, Inspection and Certification (TIC) sector.
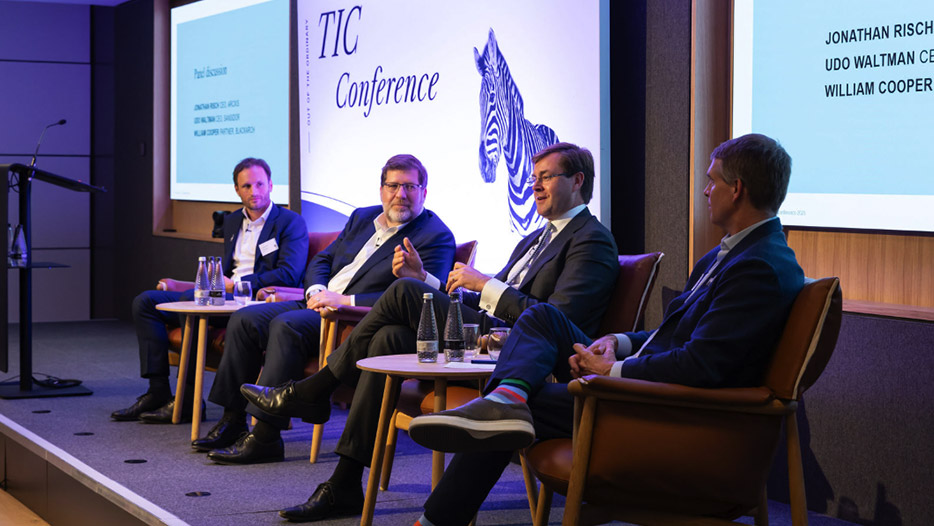
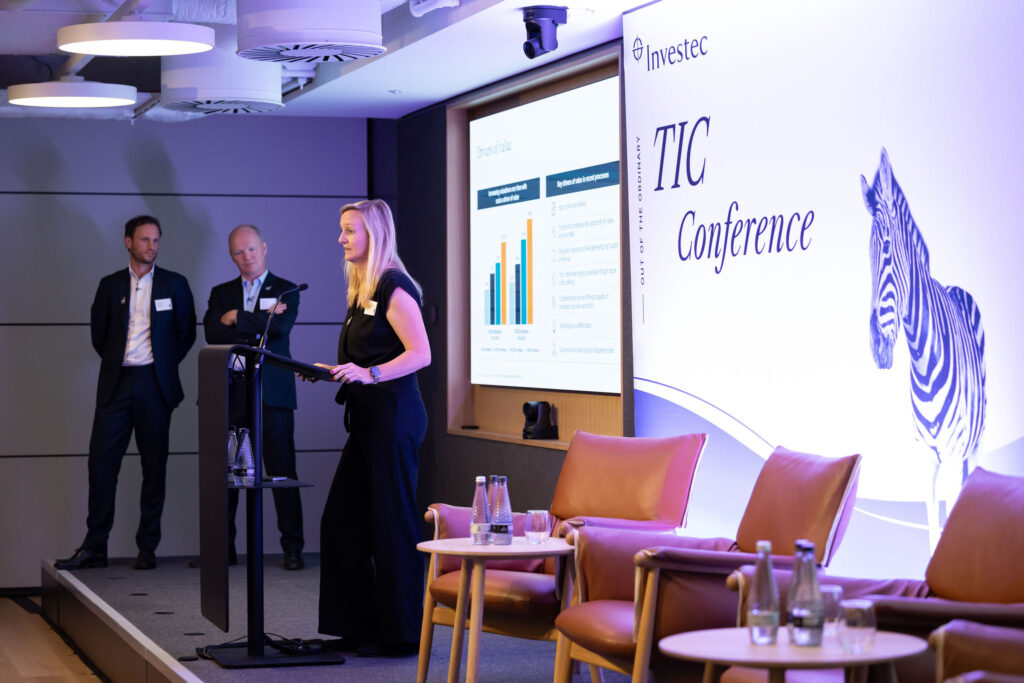
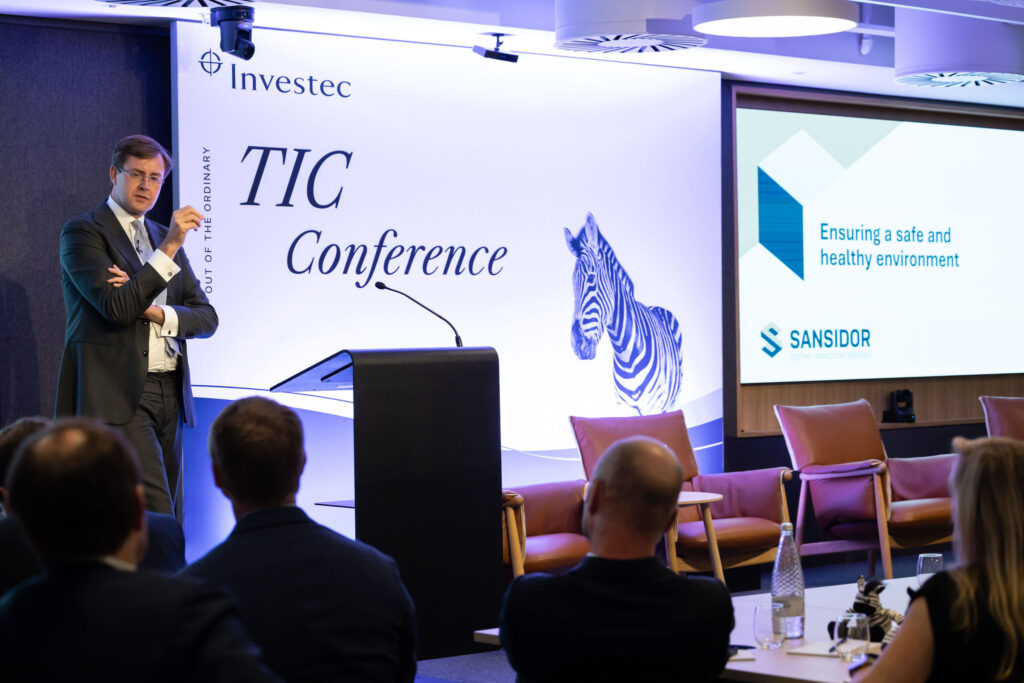
Regulatory developments, technological innovation and evolving client needs are the three biggest drivers of future opportunities to expand earnings, boost valuations and accelerate corporate activity, according to a panel of CEOs presenting at Investec’s TIC conference in London.
Regulatory demands
Regulation remains one of the biggest engines of demand. From construction to pharmaceuticals to healthcare, compliance pressures are ratcheting up across most sectors. Stringent EU directives require continual testing and certification, making third-party TIC services essential for accessing domestic and international markets.
The European TIC market is set to reach over $60 billion this year, with a projected CAGR of 5.3% by 20301. Increasing government, corporate, and consumer standards will drive growth, with tech-enablement and innovative software solutions becoming increasingly important for compliance delivery.
However, it is imperative that TIC providers ensure they bring an “economic value proposition” as well as technical benefits, according to Hugo Cence, founder and CEO of Ekoscan.
Replicability: standardising success
There is increasing demand for replicable and standardised solutions, particularly as providers expand their reach. Jonathan Risch, CEO at Arcxis outlined how important it is to “maintain consistency and quality through rapid growth”. Digitisation and automation have a major role to play in meeting that requirement.
Remote monitoring is facilitating a shift from periodic spot checks to continuous, embedded monitoring. Tech-enabled solutions are also driving efficiency and service advancements, moving TIC providers into roles that deliver ongoing value rather than one-off certification.
This creates opportunities for platforms that streamline workflows, reduce costs, and scale operations. The rise of ‘plug-and-play’ solutions also means that players with proven digital capability are well placed to take share from legacy providers – a dynamic already reflected in recent bolt-on deals.
Seamless servicing: beyond the test
Developing integrated testing, inspection and servicing solutions is another area of growth. Several TIC providers are not just flagging compliance failures but offering problem solving solutions. For example, a failed fire safety inspection could be resolved at the point of service with the tester managing on behalf of the client the supply and installation of required extinguishers.
These add-ons foster deeper, stickier client relationships and drive incremental revenue streams. As outlined by Udo Waltman, CEO at Sansidor, “We’re in a service business. If we don’t focus on what our customers need and want and how to make them successful, we won’t be successful”. Investors in the sector are actively targeting businesses that can digitise the compliance cycle and leverage client data for cross-sell opportunities, reinforcing TIC’s potential to shift from check-box expenditure to value-added partnerships.
Industry fragmentation to drive deals
M&A activity in the TIC sector has seen strong and steady growth since the reopening of markets following the COVID-19 pandemic, with sector activity reaching an all-time high of 153 transactions in the trailing twelve months to June 2025. Turbocharged growth of PE-backed, TIC buy-and-build platforms such as Phenna and Normec, alongside ongoing growth and consolidation by the listed TIC majors, have been key factors in driving increased activity levels in the sector. Europe has continued to be a dominant region for the sector, with over 65% of transactions involving a European target company.2
TIC M&A transactions – trailing twelve months
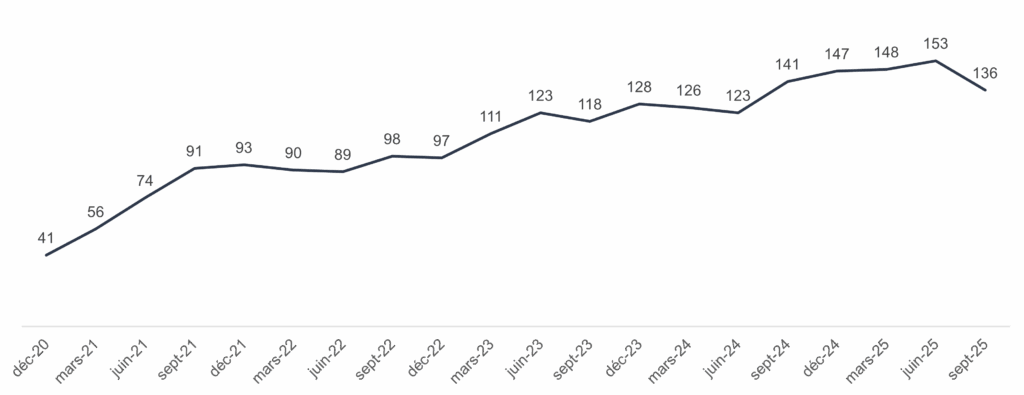
Source: Mergermarket. Based on acquisitions completed by a diversified set of companies across the TIC sector alongside select private equity acquisitions of TIC platforms
While M&A volumes in the sector have continued to grow, the TIC sector has seen an increase in acquisition valuations – across both <£25m and >£25m revenue TIC companies. Key drivers over the past 5 years include continued activity by larger private equity backed and listed consolidators as well as ongoing, high levels of investment by private equity into the sector – driving EBITDA multiples to c.15.0x for scaled TIC providers:
Increasing valuations over time with scale a drive of values
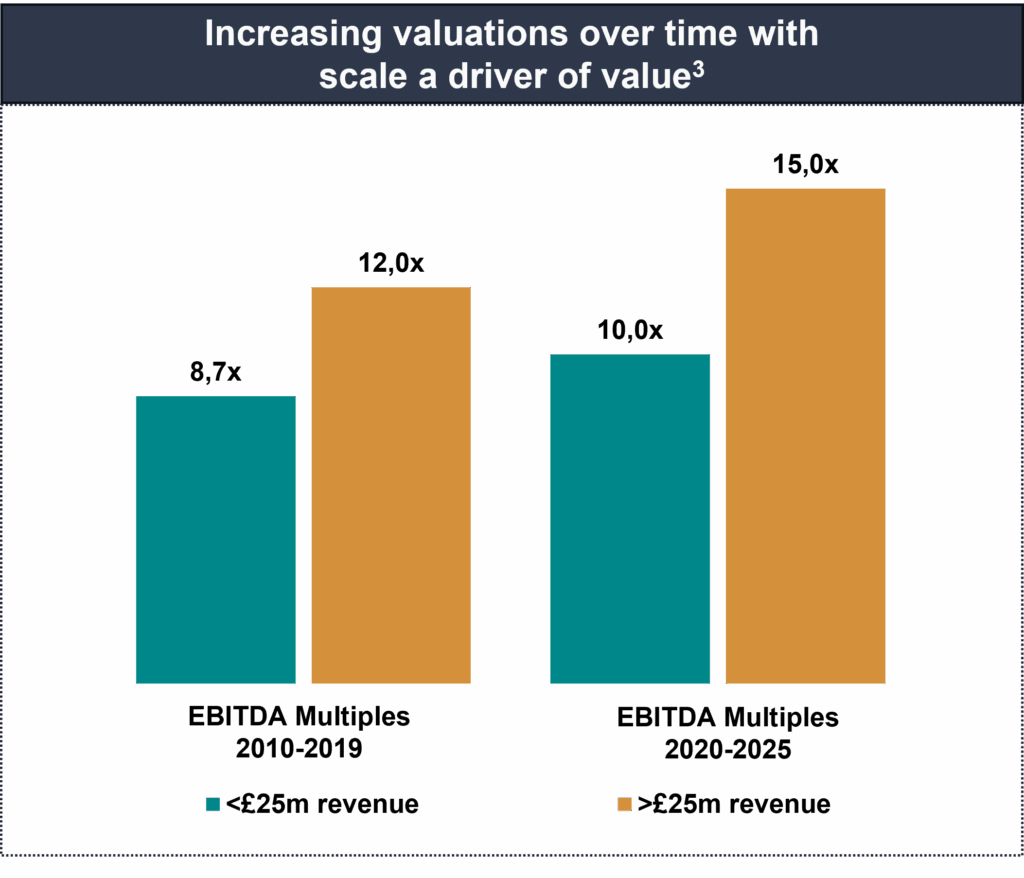
Source: Investec internal deal database: 2010 to 2025
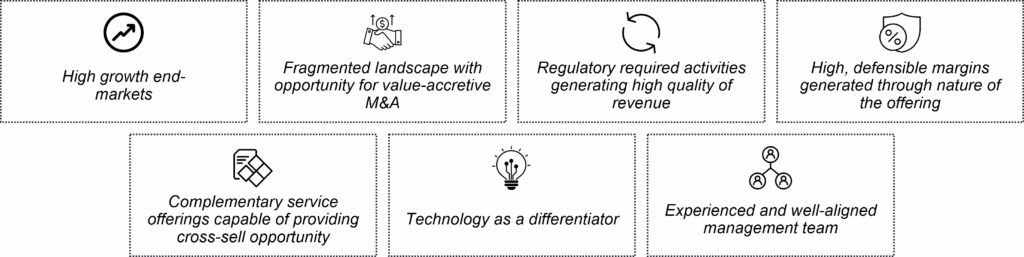
Key drivers of value in recent processesRecent transactions in the sector have highlighted several key themes as drivers of value, including i) underlying market growth dynamics, ii) differentiation leading to high, defensible margins, and iii) the ability to drive growth through M&A and complementary service offerings – driving cross sell:
Key drivers of value in recent processes
Resilience and outlook
The European market’s resilience and growth potential remain strong. Investment in platforms that can anticipate regulatory shifts, embed technology, and deliver complementary, client-led solutions will be key to capturing future opportunities. With compliance demands only increasing, standardisation and scalability are imperative. M&A activity shows little sign of easing, making the sector one of the most attractive areas for investors and corporates that embrace transformation.
TIC Conference 2025 Gallery
Footnotes:
1 Mordor Intelligence
2 Source: Mergermarket. Based on acquisitions completed by a diversified set of companies across the TIC sector alongside select private equity acquisitions of TIC platforms
3 Source: Investec internal deal database: 2010 to 2025
How a professional dialogue is now moving companies forward
Interview with Thorsten Gladiator, Managing Partner of Investec about how a professional dialogue is now moving companies forward:
- Why companies should entertain a professional dialogue with their investors and lenders?.
- What other challenges are companies facing?
- As a financial expert and transaction specialist what advice do you have for companies when dealing with debt and equity investors?
- Giving an example.
This video answers these questions and give you an idea and overview in a few minutes.
Finding the right type of capital and investor to help grow your business
Our team has a long track record of successfully raising equity and debt capital and has the necessary expertise and networks:
- Raising capital to support business growth
- Securing capital from private equity and/or other Investors to support MBO/MBI projects
- Securing capital from private equity and/or other investors to manage changes in the shareholding structure (such as supporting the buyout of one or more shareholders and the reallocation of equity shares)
- Project financing: supporting companies in realizing essential investments or working capital
- Refinancing: supporting companies in reorganizing/reducing their debt burden
Rental as a resilient and scalable solution
In an economy with uncertainty, capital preservation, and a growing appetite for flexibility, the European rental market has emerged as a resilient and fast-growing sector. Driven by small and mid-sized enterprises (SMEs) seeking to reduce capital expenditures and increase operational agility, equipment rental has transitioned from a cyclical option to a strategic business choice. This shift is further fuelled by increasing ESG and sustainability priorities, as rental models enable more efficient resource use, promote circularity, and reduce environmental impact.
In 2024, the global equipment rental market reached $153.7 billion, with Europe accounting for $37 billion and the Netherlands contributing $6.3 billion. Notably, the Dutch rental market is expected to grow at a 5.5% CAGR through 2029, outperforming the European average of 5.2% and closely aligning with global growth expectations.
Resilient growth across key rental verticals
The equipment rental sector spans a wide range of segments, each with unique drivers and robust long-term outlooks:
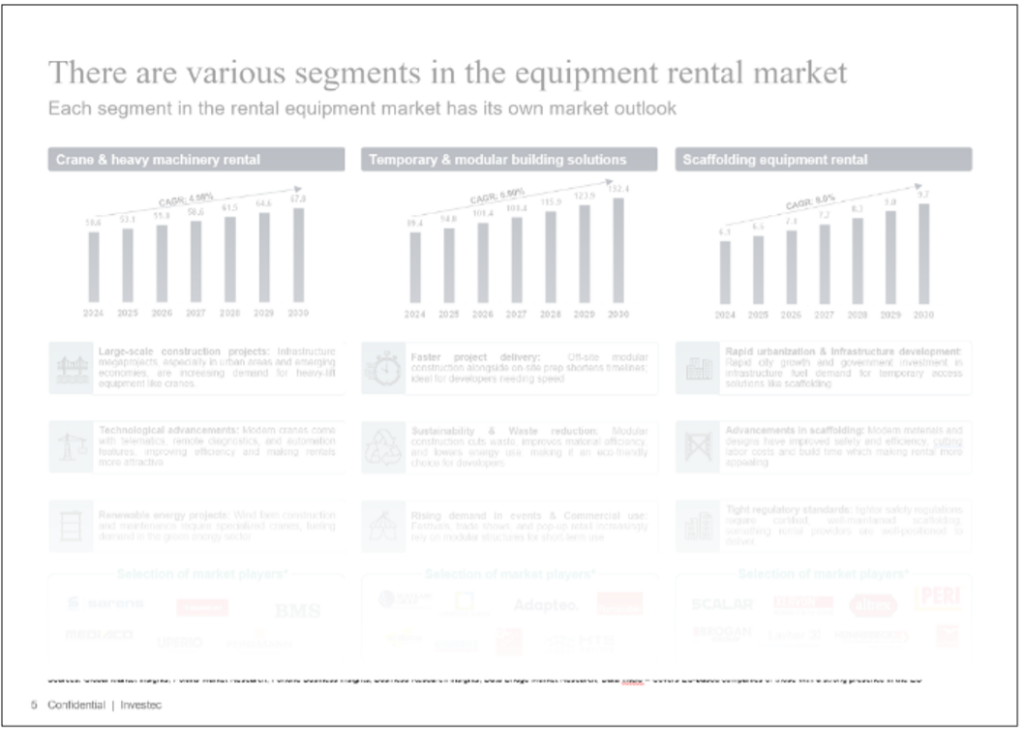
- Scaffolding Equipment Rental (CAGR: 8.0%): Fuelled by stricter safety regulations, rapid urbanization and construction
- Temporary & Modular Buildings (CAGR: 6.9%): A key enabler for sustainable construction, fast project turnaround, and events infrastructure
- Cranes & Heavy Machinery (CAGR: 4.98%): Supported by infrastructure megaprojects and renewable energy investments
- HVAC & Energy Solutions (CAGR: 4.3%): Essential for healthcare, emergency events, and large-scale construction
- AV & IT Equipment Rental: (6.3%) CAGR: Increasingly driven by hybrid work, online education, and rapid tech innovation
M&A: a consolidating and competitive landscape
After a slight dip in 2023, M&A activity in the rental sector rebounded in 2024, signalling increased confidence in the market. Strategic buyers continue to dominate, accounting for over 50% of all transactions, with strong interest in regional champions and niche rental categories.
According to Investec’s proprietary analysis of ~500 European rental transactions between 2020 and 2024:
- The UK led with 89 deals, followed by France (62), DACH (57), the Nordics (43), and Benelux with 27, home to key consolidators such as Boels.
- The sector sees a relatively high proportion of domestic transactions, particularly in France where 87% of deals remain within national borders.
Meanwhile, large platforms like Ashtead, Kiloutou, and Boels are acquiring in adjacent segments such as mobile lighting, modular buildings, and HVAC, highlighting a growing preference for product/equipment diversification and full-service offerings.
Valuation multiples for listed rental players have recovered in 2025, with average EV/EBITDA rising from 6.0x in 2024 to 6.4x, and the median multiple hitting 7.4x.
Increased interest of financial buyers
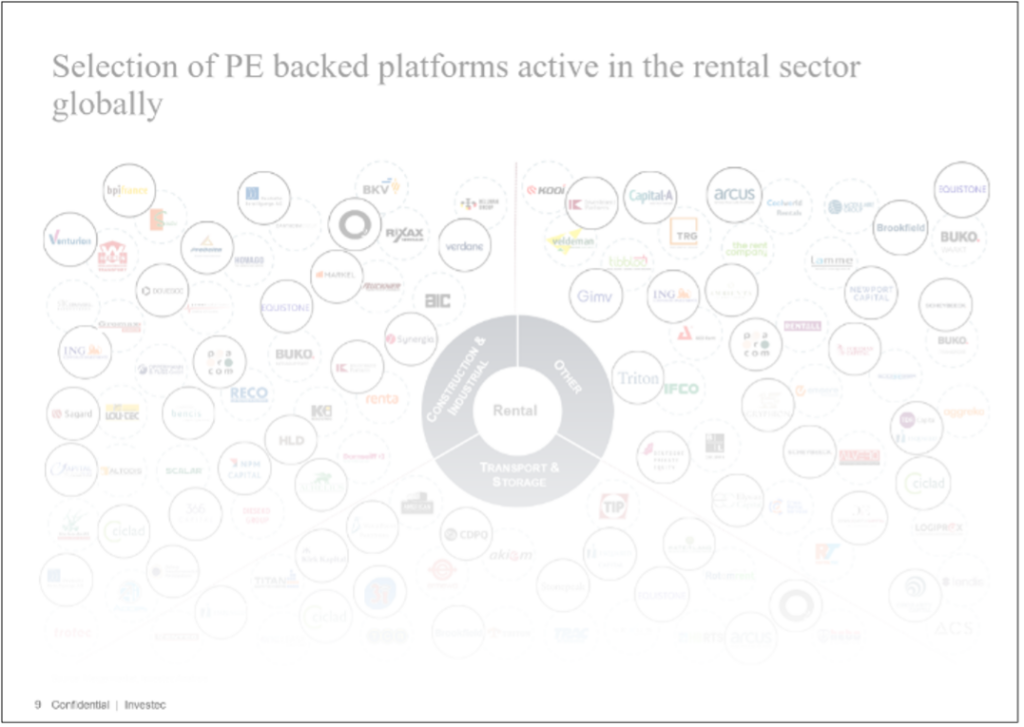
Rental businesses’ robust financial fundamentals, high asset utilisation, and repeat customer models have not gone unnoticed. The share of transactions executed by financial buyers rose from 21% in 2023 to 32% in 2024, highlighting their increased interest in the market.
In the Benelux, investors such as Parcom, 365 Capital, ING Corporate Investments, IK Partners, Capital A, Down2Earth Capital, GIMV, and more have (recently) acquired assets in the rental sector.
Investec has advised on numerous rental transactions, including the sale of:
- Coolworld Rentals – a specialist in sustainable HVAC solutions, to GIMV
- Stravers Torenkranen – a leading European supplier of electric tower crane solutions, sold to ING Corporate Investments
- Tibbloc – the French leader in temporary energy systems, backed by Cilclad, also to GIMV
Looking ahead
A growing preference for flexibility and reduced capital intensity is driving more businesses to integrate rental into their operating models. This shift also supports sustainability goals by promoting reuse, reducing waste, and extending asset lifecycles, which is becoming increasingly important to businesses and regulators.
M&A activity is set to keep growing, especially in certain niches and fragmented geographies. Both strategic and financial investors remain interested in the broad diversity of rental applications, platforms and recurring revenue streams.
At Investec, we believe the rental sector offers an exceptional blend of resilience, innovation, and long-term opportunity, making it one of the most compelling spaces in the European mid-market.
For more information and our full 2025 Rental Report, please contact Marleen Vermeer or Thom Deckers.
Trends in the T&L Market
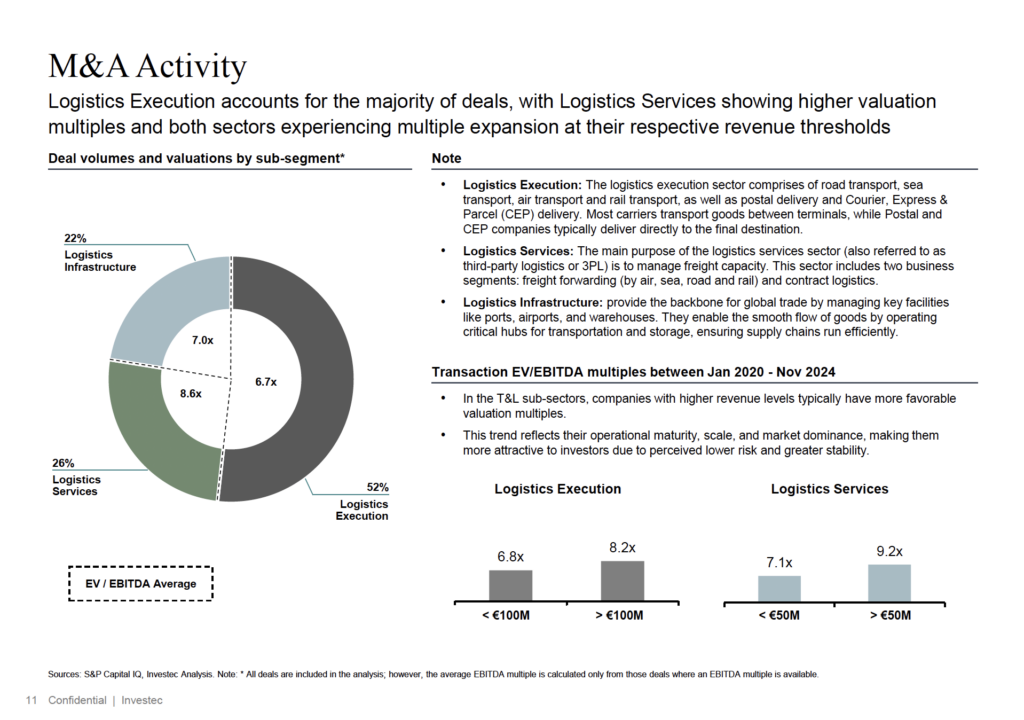
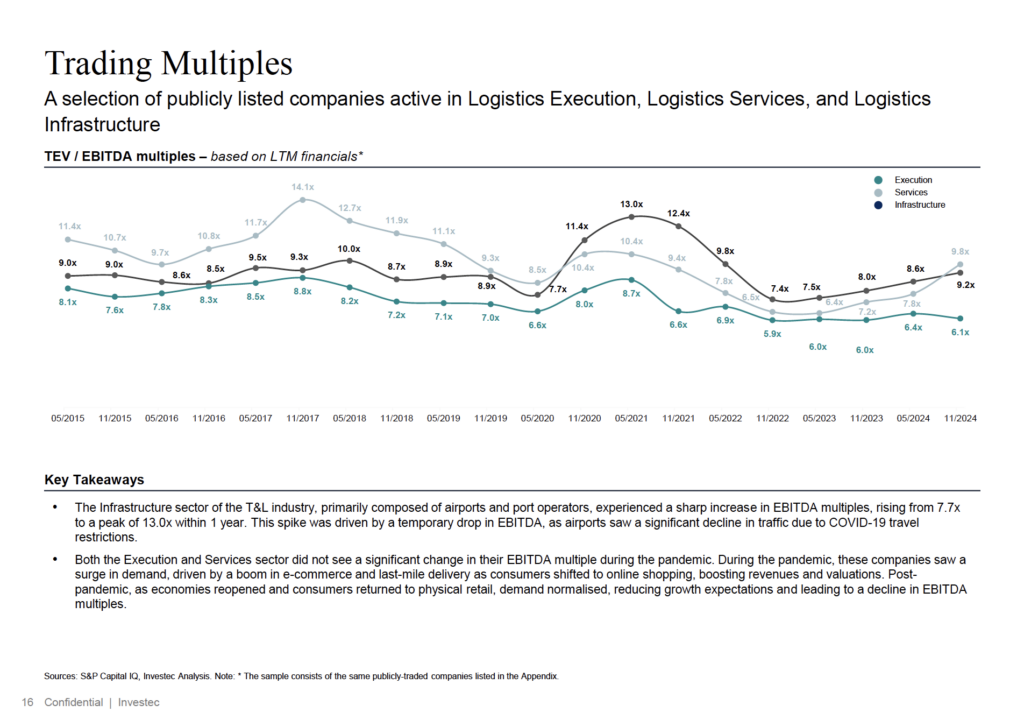
The European T&L sector has seen robust M&A activity, with around 1,250 transactions recorded between 2020 and 2024. Market consolidation is driven by strategic buyers and private equity investors, particularly in logistics execution, services, and infrastructure. The UK, France, and the Nordics lead in deal volume. Companies with scalable operations and strong digital capabilities are often valued more highly, as investors prioritize assets that are well-prepared for future growth.
Benelux Market
Benelux remains a key hub for T&L M&A, ranking among the most active European regions for cross-border transactions. Approximately 60% of deals involve international buyers, with UK and Nordic investors being particularly active. The region’s strong logistics infrastructure, central location, and established trade networks make it an attractive target for strategic and financial buyers alike.
Private equity continues to play a significant role in market consolidation, with financial sponsors accounting for ~31% of acquisitions. This trend reflects growing investor interest in scalable logistics platforms and high-performing supply chain assets.
For more insights and our full 2024 T&L M&A report, please contact Jan Willem Jonkman.
Helen Lucas | UK
Jonathan Harvey | UK
Our 14th report comes at a crucial time for the industry, as GPs get back to the business of selling portfolio companies and raising new funds.
2024 was a tough year for private equity and the overriding view from our survey of 253 general partners (GPs)* is that 2025 will be different.
Our findings show an industry which, despite challenges over the past few years, is resilient, adaptable, and anticipating a more favourable period ahead.
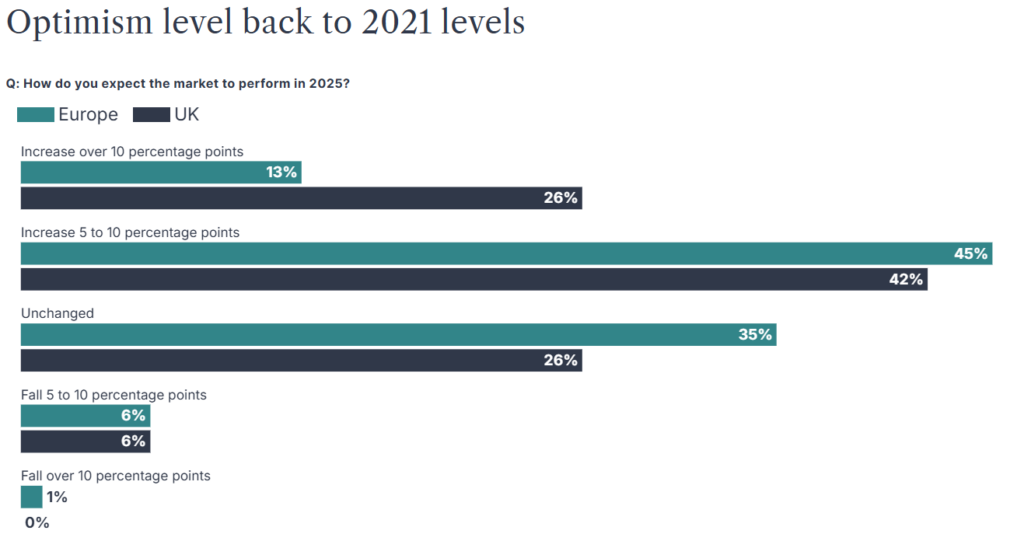
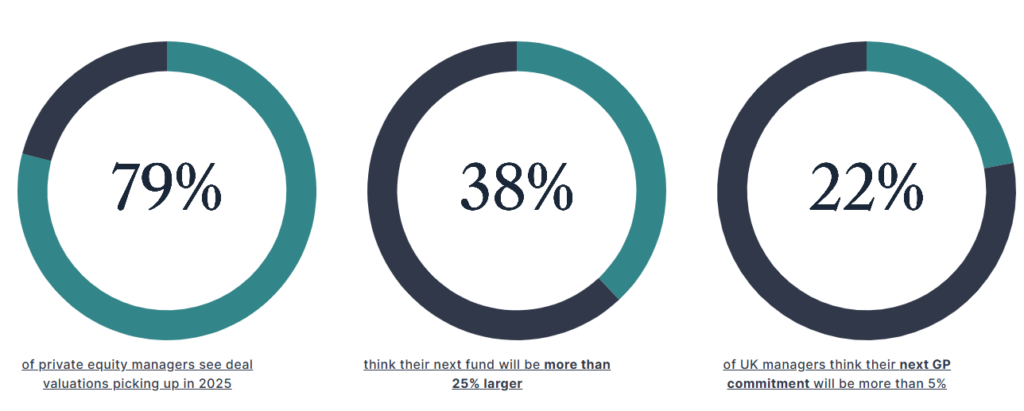
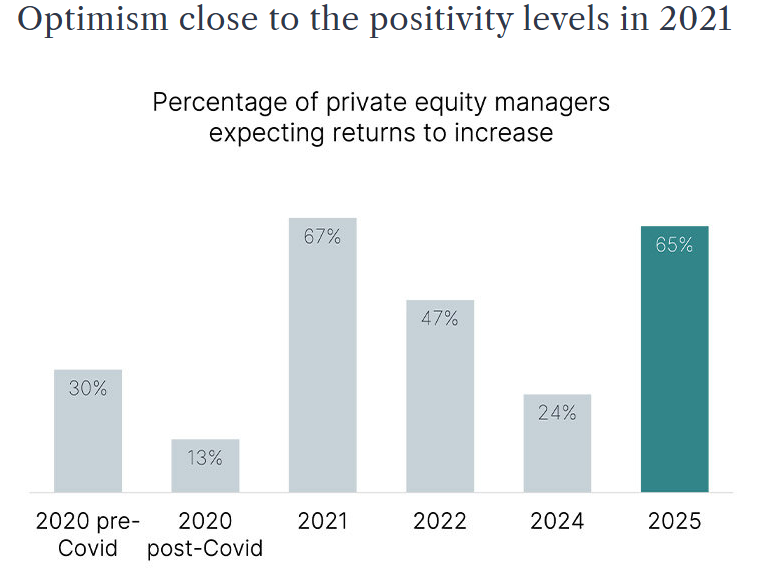
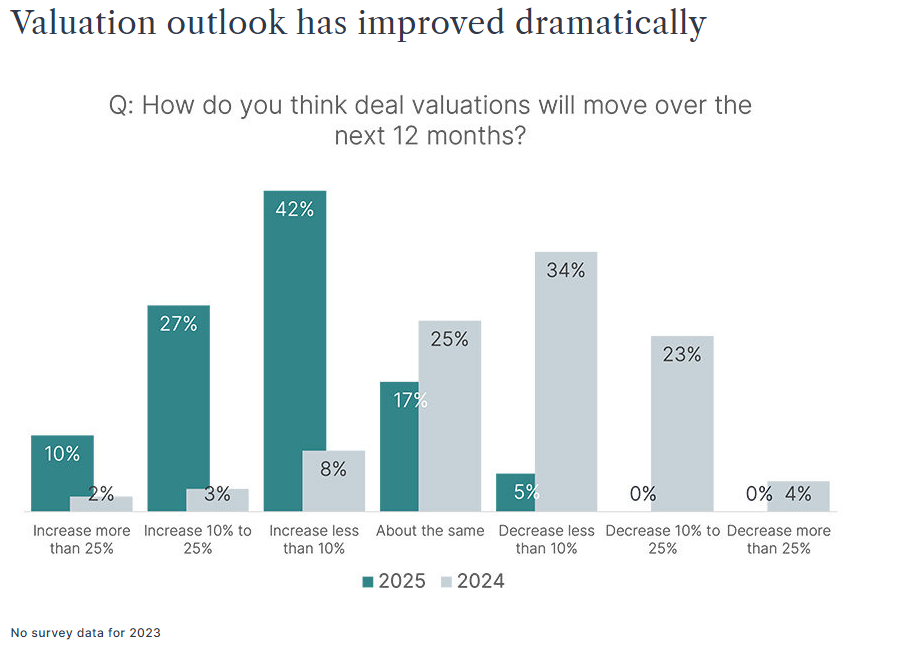
Four in five GPs expect deal valuations to increase in 2025 as interest rates come down, helping to clear exit bottlenecks and accelerate investors’ distributions. The outlook for returns is also brighter, with improvements registered across geographies and fund sizes. Close to two thirds (65%) of investors see returns improving in 2025, up from only 24% in 2024.
Dealmakers still must navigate ongoing geopolitical and macroeconomic risk, as trade tariff tit-for-tats continue and conflicts in the Middle East and Ukraine remain unresolved. It is a complex market, but the backdrop for M&A is better than it was a year ago.
Jump to a section:
Future fundraisings
GP commitments
New world of debt
Innovations and exits
GPs at a crossroads
Future fundraisings
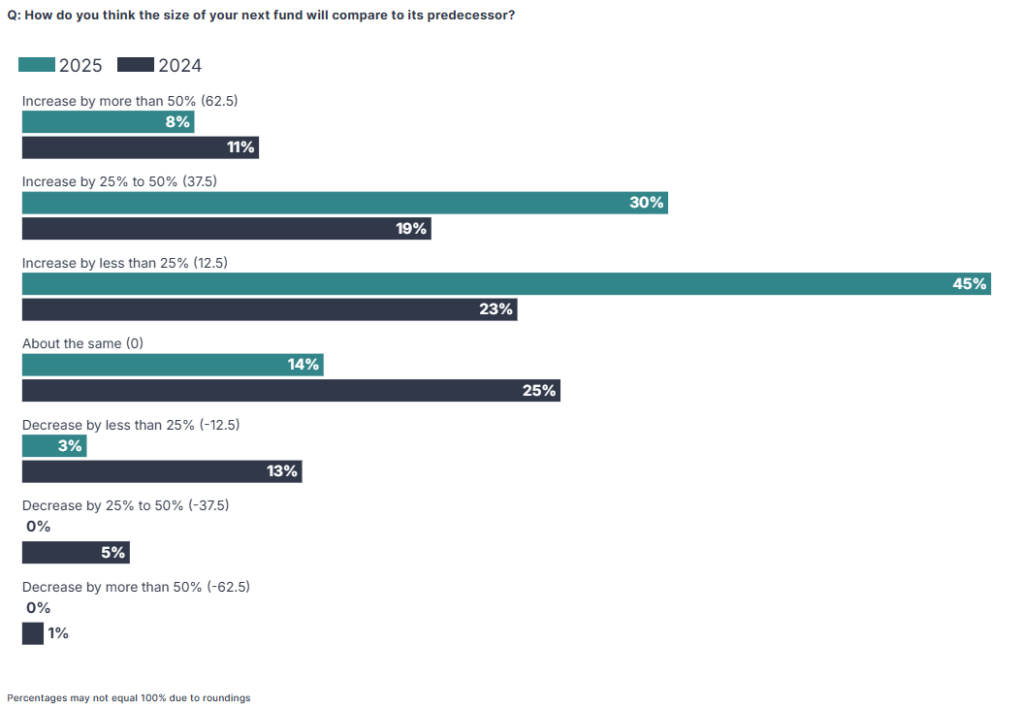
In 2024, 21% of respondents expected a down raise for their next fund: the 2025 research shows only 3% anticipating the same scenario.
There is also a large cohort of super-optimists – 38% expect their next raise will be a blockbuster increase of 25% or more over their previous fund.
Limited partners (LPs), however, are expected to remain highly selective in 2025. In 2024, according to PEI figures1, the ten largest funds to close in 2024 all secured more than $10 billion and absorbed more than a fifth of total fundraising allocations while a Coller Capital LP survey2 showed that the top focus for 98% of investors is that a new manager has a team with a strong track record.
Our survey findings tie in with this theme – close to a third of respondents (31%) expect an increasing number of GPs to move into wind-down. However, this does not mean the opportunity for new managers has passed; just 26% agreed that “very few new GPs will be launched”.
Although fundraising conditions are improving, LPs continue to consolidate GP relationships, focusing on managers of scale and mid-market specialists with differentiated investment strategies and exceptional returns.
Fundraising optimism surges
Jump to a section:
Deal valuations
GP commitments
New world of debt
Innovations and exits
GPs at a crossroads
GP commitments
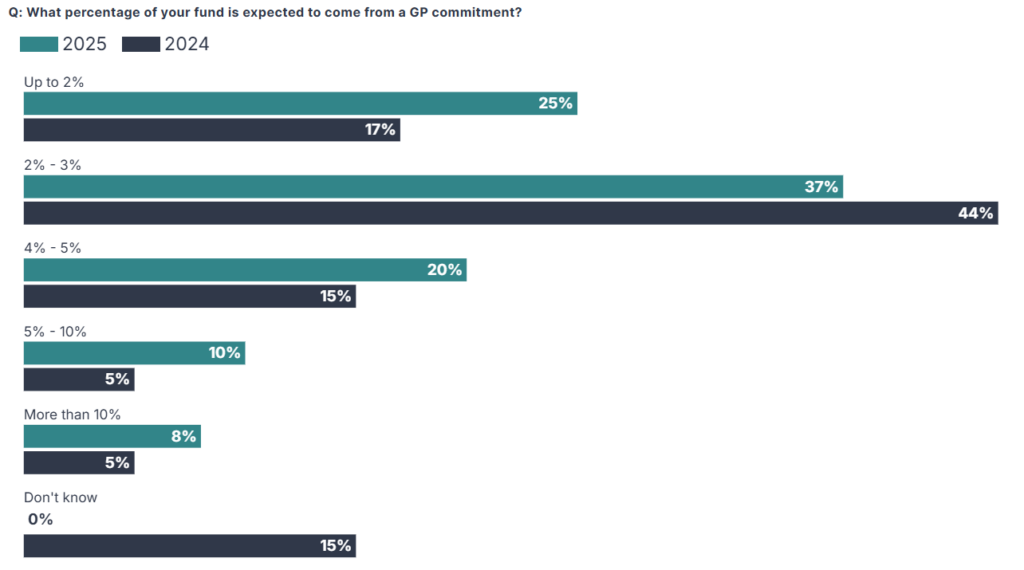
The survey shows GPs are planning to up their commitment from the typical 2% to 3% to strengthen alignment with investors and boost fundraising momentum.
- One in five GPs expect to commit 4-5% of their next fundraise.
- One in ten expect their next commitment to be 6-10%.
- 8% expect to commit more than 10% in 2025.
Managers are taking a blended approach to financing these higher commitments including existing resources, reinvesting carried interest and external debt, which is gaining favour. Most are using two options to fulfil their obligations, with 13% expecting to use three options.
Where are commitments highest?
The findings reveal interesting regional variations when it comes to GP commitments.
UK managers are more likely to be asked for a big commitment: 22% were asked for more than 5% versus just 8% of managers in Europe. Managers in France, meanwhile, seem to be asked for a particularly slim commitment, with more than half expecting to be asked for less than 2%.
Overall, a significant minority of investors expect to up commitments in the future.
Jump to a section:
Deal valuations
Future fundraisings
New world of debt
Innovations and exits
GPs at a crossroads
New world of debt
Debt markets are open for business with a substantial number of new lenders entering the market to provide GPs with enhanced financing optionality.
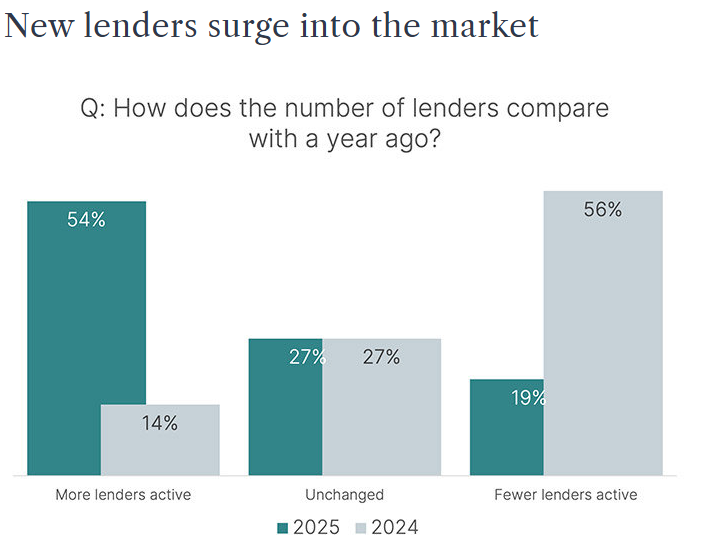
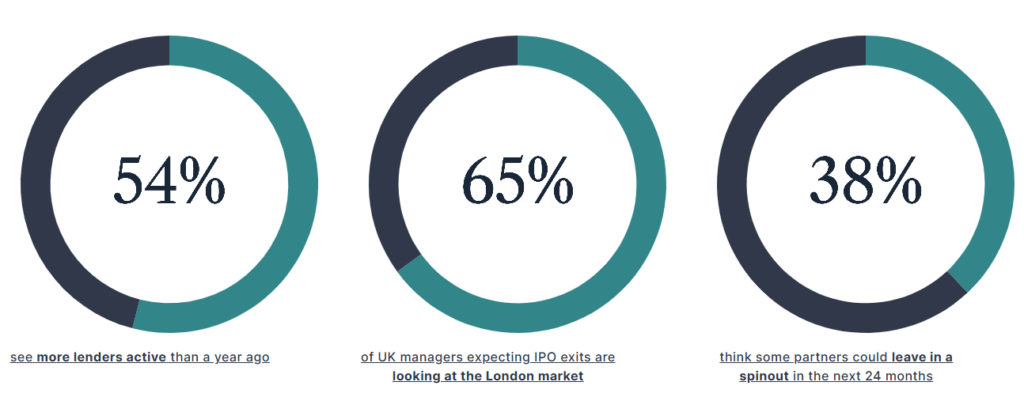
More than half (54%) of GPs say they will have new lenders to work with in 2024. This marks a shift from last year’s findings, when 56% of respondents saw a contraction in new lender activity. The majority of GPs who took part in our survey are working with credit funds and the top three reasons cited for working with a private credit included higher leverage levels and innovative financing solutions.
UK managers are hopeful that increasing competition will result in looser terms, with 54% of UK managers reporting either private debt narrowing margins or terms loosening generally. Outside of the UK, however, GPs are more cautious, with only 35% forecasting looser terms.
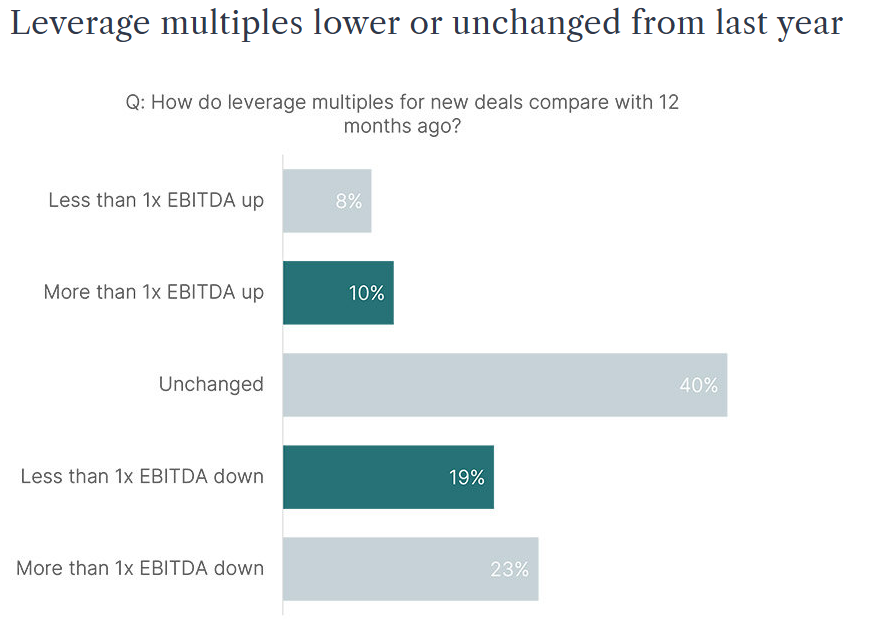
Despite these expectations, lenders are remaining disciplined. Well over a third of respondents (43%) report that leverage multiples have lowered from a year ago.
Competition is fierce for trophy assets in certain sectors, and these companies will be able to negotiate more favourable terms, but lenders will be highly selective.
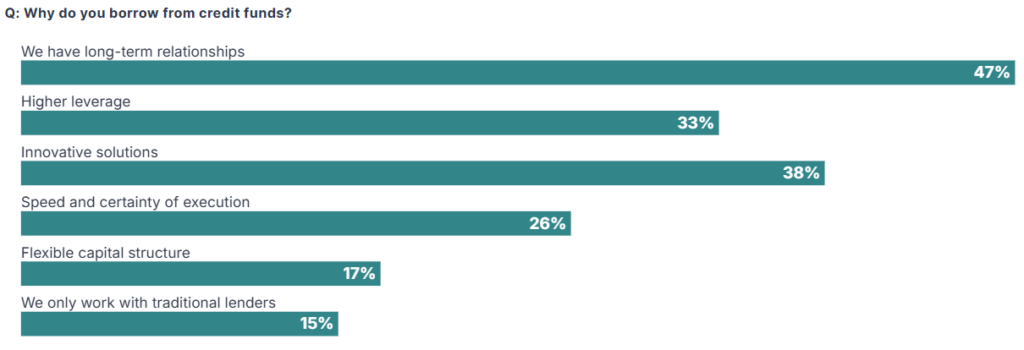
Interest rates may have come down, but the risk-free rate remains elevated when compared with recent years, making additional leverage costly to service. Debt is available (European leveraged loan issuance climbed by more than 90% in 20243 and private debt managers have $126.4 billion of dry powder available to invest4), but the survey findings on leverage multiples show that capital structures remain relatively conservative.
Covenant flexibility
Even as interest rates have come down, GPs have still had to work hard to protect portfolio companies.
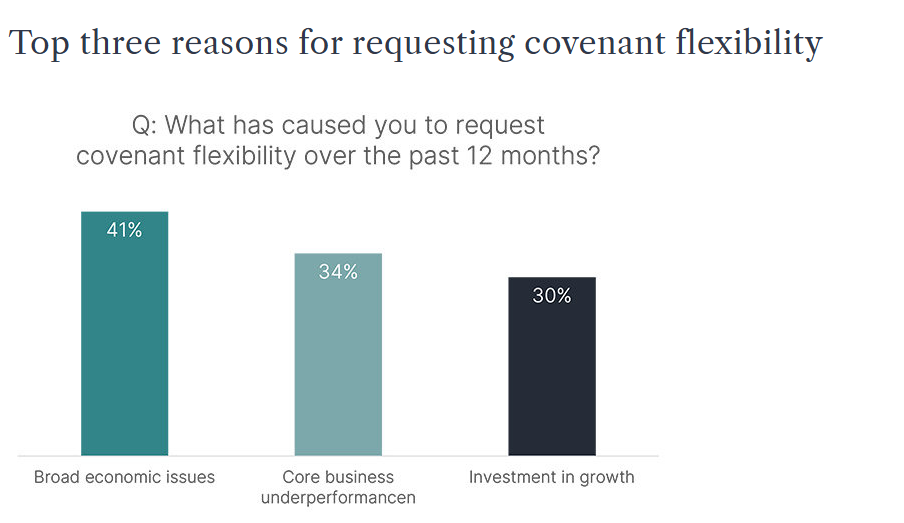
Some 87% of respondents say they have gone to lenders to request covenant flexibility for one or more portfolio companies. Broad economic issues (cited by 41%) and business underperformance (cited by 34%) are the main reasons for requesting flexibility.
Interestingly, close to a third of respondents (30%) have requested covenant flexibility to fund growth as GPs hold some portfolio companies for prolonged periods.
“We will always be open to a conversation about covenant flexibility. If a business is growing and wants to re-lever, or the sponsor wants to hold an asset for longer, loosening covenants can have a positive impact on supporting growth.” – Helen Lucas, Co-Head of UK Origination, Direct Lending, Investec
Lending landscape
As more lenders entered the private equity space, there has also been increased use of some newer debt products. Innovation continues; survey respondents expect ESG-linked lending, fund-level finance and asset-based lending to increase market share.
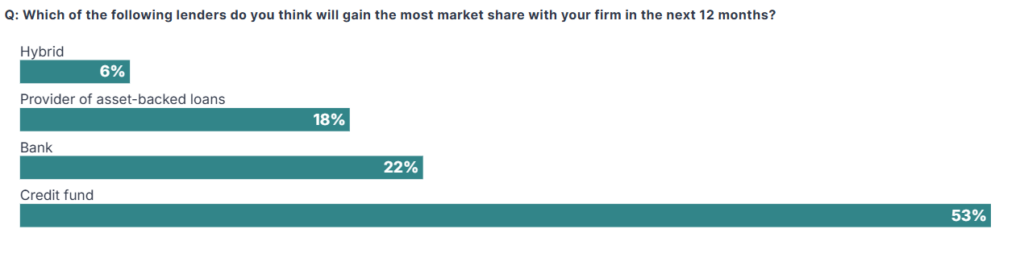
Around half of the respondents expect credit funds to do more business with their firm during the year, but banks remain highly competitive; almost a quarter (22%) say they expect to place more lending with banks in the next 12 months. Hybrid capital is gaining particular traction for smaller managers with assets of $250m or less, with a quarter of these saying this type of lender will gain the most market share at their firm in the next year.
NAV lending
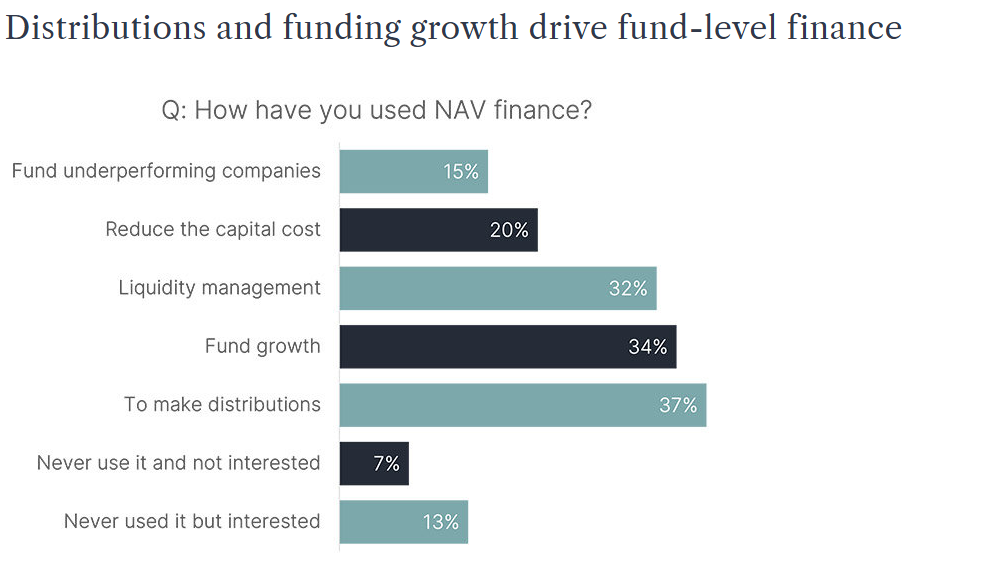
Net asset value (NAV) finance has proven particularly popular with managers in an environment where liquidity has been constrained.
Four in five GPs said they used NAV finance in the last year, with distributions the most-cited use case (37%).
Uptake of NAV finance looks set to continue accelerating, with two thirds (65%) of respondents who had not used NAV finance previously saying they were interested in taking up NAV loans.
Deployment and operations
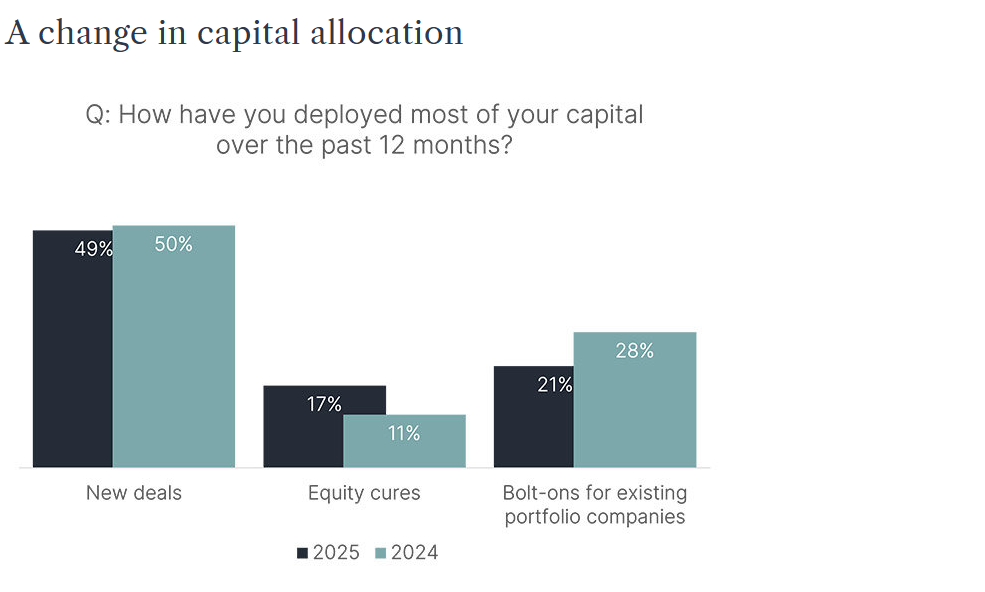
Less than half of GPs (49%) have deployed most of their capital in new deals during the past 12 months, with just over a fifth (21%) focusing efforts on smaller bolt-on acquisitions to support buy-and-build portfolios – down from 28% in our previous survey. An increase in the number of GPs deploying most of their capital in equity cures – up to 17% from 11% last year – further highlights the tough backdrop for managers during the past year.
The improving outlook means that the next 12 months should be more favourable for deployment. Somewhat surprisingly, the public-to-private outlook is mixed and not much changed from last year despite low stock market valuations, most notably in the UK5. Some 50% say they expect to look at more public-to-privates but 40% expect to look at less.
Big-ticket take-private deals during 20246 have ensured that P2P remains on the managers’ radars and may result in activity in this area.
“Private equity managers are ready to deploy, but it is taking much longer to originate deals. GPs will be forming relationships with management teams up to three years ahead of a formal process. During the last two years we have seen a number of processes fall over, and it does take time to rebuild before businesses come back to market.” – Kate Gribbon, Head of Financial Sponsor Coverage & Origination, Investec
Jump to a section:
Deal valuations
Future fundraisings
GP commitments
Innovations and exits
GPs at a crossroads
Innovations and exits
One of the single biggest challenges for private equity managers through the rising interest-rate cycle has been to sell portfolio assets at valuations that deliver adequate returns.
In tepid IPO and M&A markets, GPs often opted to sit tight rather than offload assets at lower-than-hoped-for multiples. Hold periods remain above long-term averages, with the backlog of private equity-backed companies sitting at record levels7.
This has had repercussions on fundraising – slowing distributions to LPs have limited their ability to allocate to new funds.
Managers looking at exits will explore all options to crystallise returns, with the survey findings ranking expectations for different exit routes in a narrow band.
More than half of GPs (54%) think trade sales will be the busiest exit route during the next 24 months. But after a long barren spell the IPO is back in the frame again, with the typical manager optimistic that two portfolio companies could be an IPO candidate over the next two years.
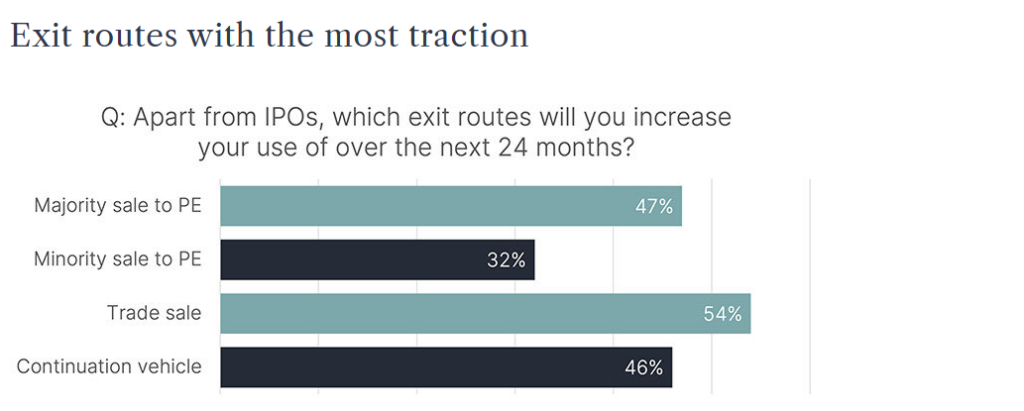
The squeeze on other exit routes meant there has been greater use of continuation vehicles which are here to stay as a mainstream exit path: more than 40% of GPs say a continuation fund will be an exit option they are more likely to use in the next 12 months.
The UK IPO question
Private equity-backed portfolio company IPOs haven’t always been crowd-pleasers, particularly on UK markets8, but the survey findings show managers warming to the UK stock market – albeit with some reservations.
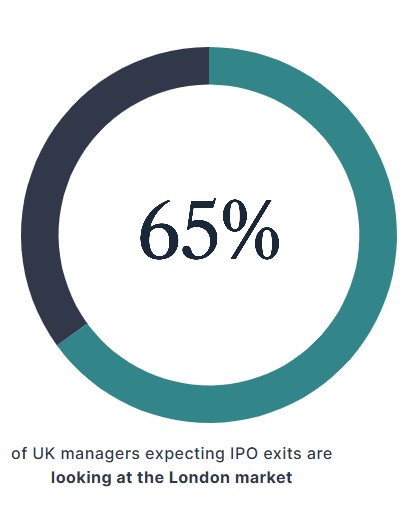
Some 65% of UK managers who expect to list a portfolio company in the next two years consider the UK a potential venue – although they will also look at other venues such as Amsterdam or New York.
The size of the manager and portfolio is a factor in stock market selection. Larger managers with bigger assets to float think a UK IPO is less attractive, indicating that larger IPOs are considered more challenging for UK public markets.
Jump to a section:
Deal valuations
Future fundraisings
GP commitments
New world of debt
GPs at a crossroads
GPs at a crossroads
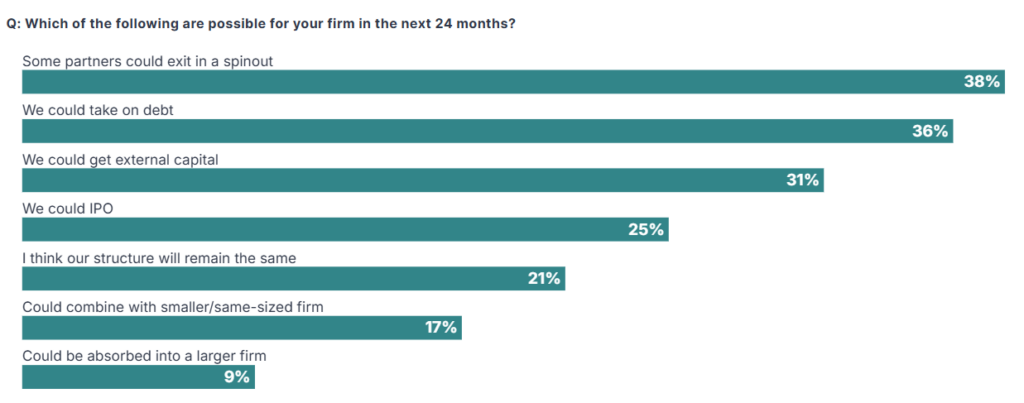
According to Pitchbook figures, GP-to-GP M&A reached record highs at the end of 20249 and the survey points to a long runway of further deals, with 79% of respondents expecting some kind of change to their firm’s structure.
In addition to GP consolidation deals, new teams are forming in spinouts and minority stake investment is proliferating.
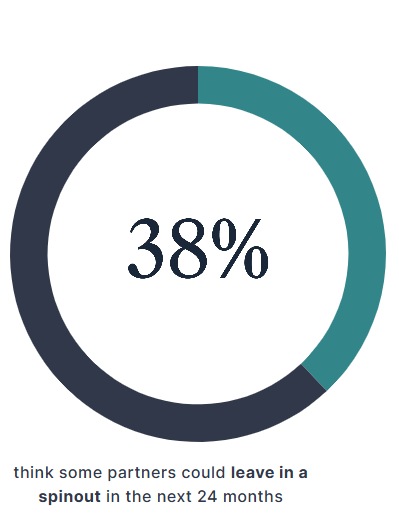
Indeed, 38% of GPs say some partners could leave their firm via a spinout in the next 24 months. This is reflective of a tougher fundraising environment, particularly for smaller managers with assets under management (AUM) below $1bn, where spinouts are more likely as junior partners explore other options when fundraisings stall.
Getting ready to capture growth
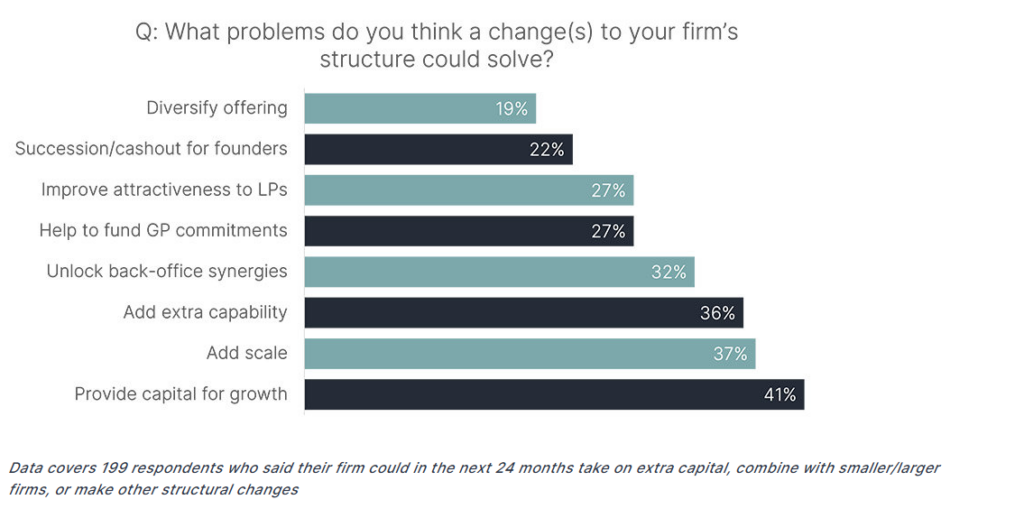
Historically, the main driver for taking on third-party capital or merging with another firm was likely to unlock liquidity and facilitate succession. While this reason was selected by 22% of respondents, the majority see a transaction as a tool to provide capital for growth or expand service lines and scale.
Ideally, twice as many managers say they would like to be the acquirer rather than target in a consolidation scenario.
What is also worth noting is that when it came to continuation vehicles, our survey showed that 40% of GPs think there will be more single-asset continuation vehicles over the next 24 months and over 25% thought they are likely to become more specialised. Single-asset continuation vehicles allow GPs to remain invested in a prized portfolio company and could potentially lead to a spin-out by a manager.
Jump to a section:
Deal valuations
Future fundraisings
GP commitments
New world of debt
Innovations and exits
* Demographic info
This report is based on 253 responses to an online survey conducted between 7 January and 22 January 2025. Respondents were sourced from a prequalified panel and no PE firm was represented more than once.
178 were based in the UK, 75 in Europe including 22 in Germany, 14 in Spain and 11 in France. Some 34% of respondents were investment directors, other eligible job titles were CFO, VP of finance, director of finance, principal and manager of finance/investments.
Footnotes:
2 https://www.collercapital.com/41-barometer-winter-2024/
4 https://www.muzinich.com/opinions/corporate-credit-outlook-2025-private-markets
6 https://www.ft.com/content/ec9aa2ae-f56a-4373-8c4b-88effc01a25d
7 https://www.mckinsey.com/industries/private-capital/our-insights/global-private-markets-report
9 https://pitchbook.com/news/articles/blackrock-hps-purchase-record-year-gp-consolidation
Market trends, Financial operations, and Valuations in the Dutch Market

“The fundamental strength of the electrical engineering sector remains evident, propelled by the accelerating push for energy efficiency, the growing adoption of renewable energy sources, and the emergence of innovative technologies”
Marleen Vermeer – Partner Investec Benelux
This report provides an overview of market trends, Financial operations, and valuations in the Dutch Market.
To access and read the full report click here
Case Study
Aqseptence Group, a global leader in autonomous water and filtration technology, equipment and system solutions specialising in water treatment and liquid/solid separation, has attracted Oaktree, a leading global investment manager, as an investor.
Oaktree’s investment and expertise will provide Aqseptence Group with the necessary resources to continue to grow and innovate to best serve existing and new markets.
Interview with Baldassare La Gaetana, CEO of Aqseptence Group and Ervin Schellenberg, Managing Partner of Investec, taking us through the process and decision making of Oaktree’s majority investment in Aqseptence in a short video:
- What is the Aqseptence Group? Why a new shareholder?
- What is your sector and investor perception? – Opinion Ervin Schellenberg
- Why is it important to work with an M&A advisor? – Opinion Baldassare La Gaetana
- How was the collaboration with Investec?
For nearly 25 years, Investec has been assisting its clients in reaching their strategic goals, whatever it takes, whether it’s by securing a strategic business, or maneuvering and winning a competitive auction process:
We are particularly adept at advising on the following situations:
- Acquiring (family-owned) companies, groups, or other mid-market companies
- Acquiring subsidiaries or business units from (international) corporates, including carve-outs
- Acquiring businesses from a founder/(majority) shareholder, including succession
- Acquiring shares owned by a private equity firm, family office or other investors
Designing and executing such transactions is what our team does on a daily basis. To ensure success, our team also leverages its extensive experience and unique capabilities, which include: deal intelligence, tactical, technical and project management skills, negotiation skills, and an understanding of the personal interests/sensitivities of relevant stakeholders.
Digital Disruption and Strategic Consolidation: Navigating the New Frontier in Industrial Services
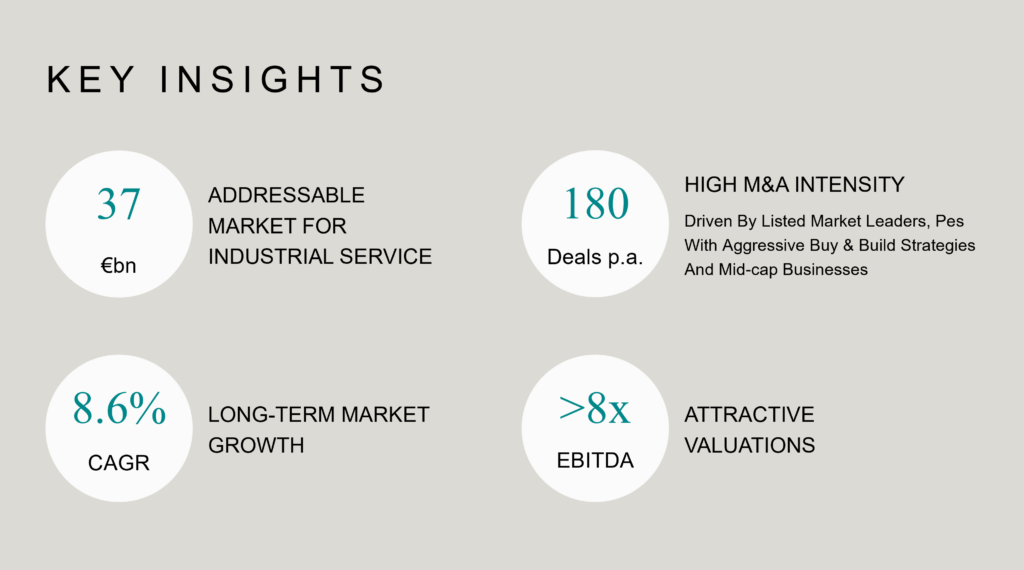
Global Industrial Service
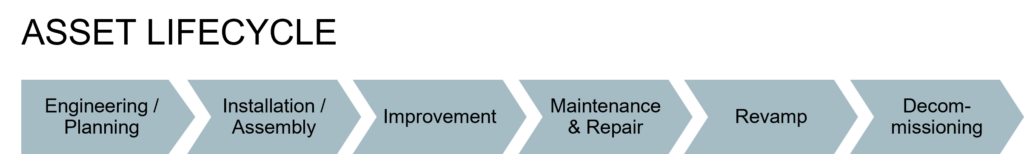
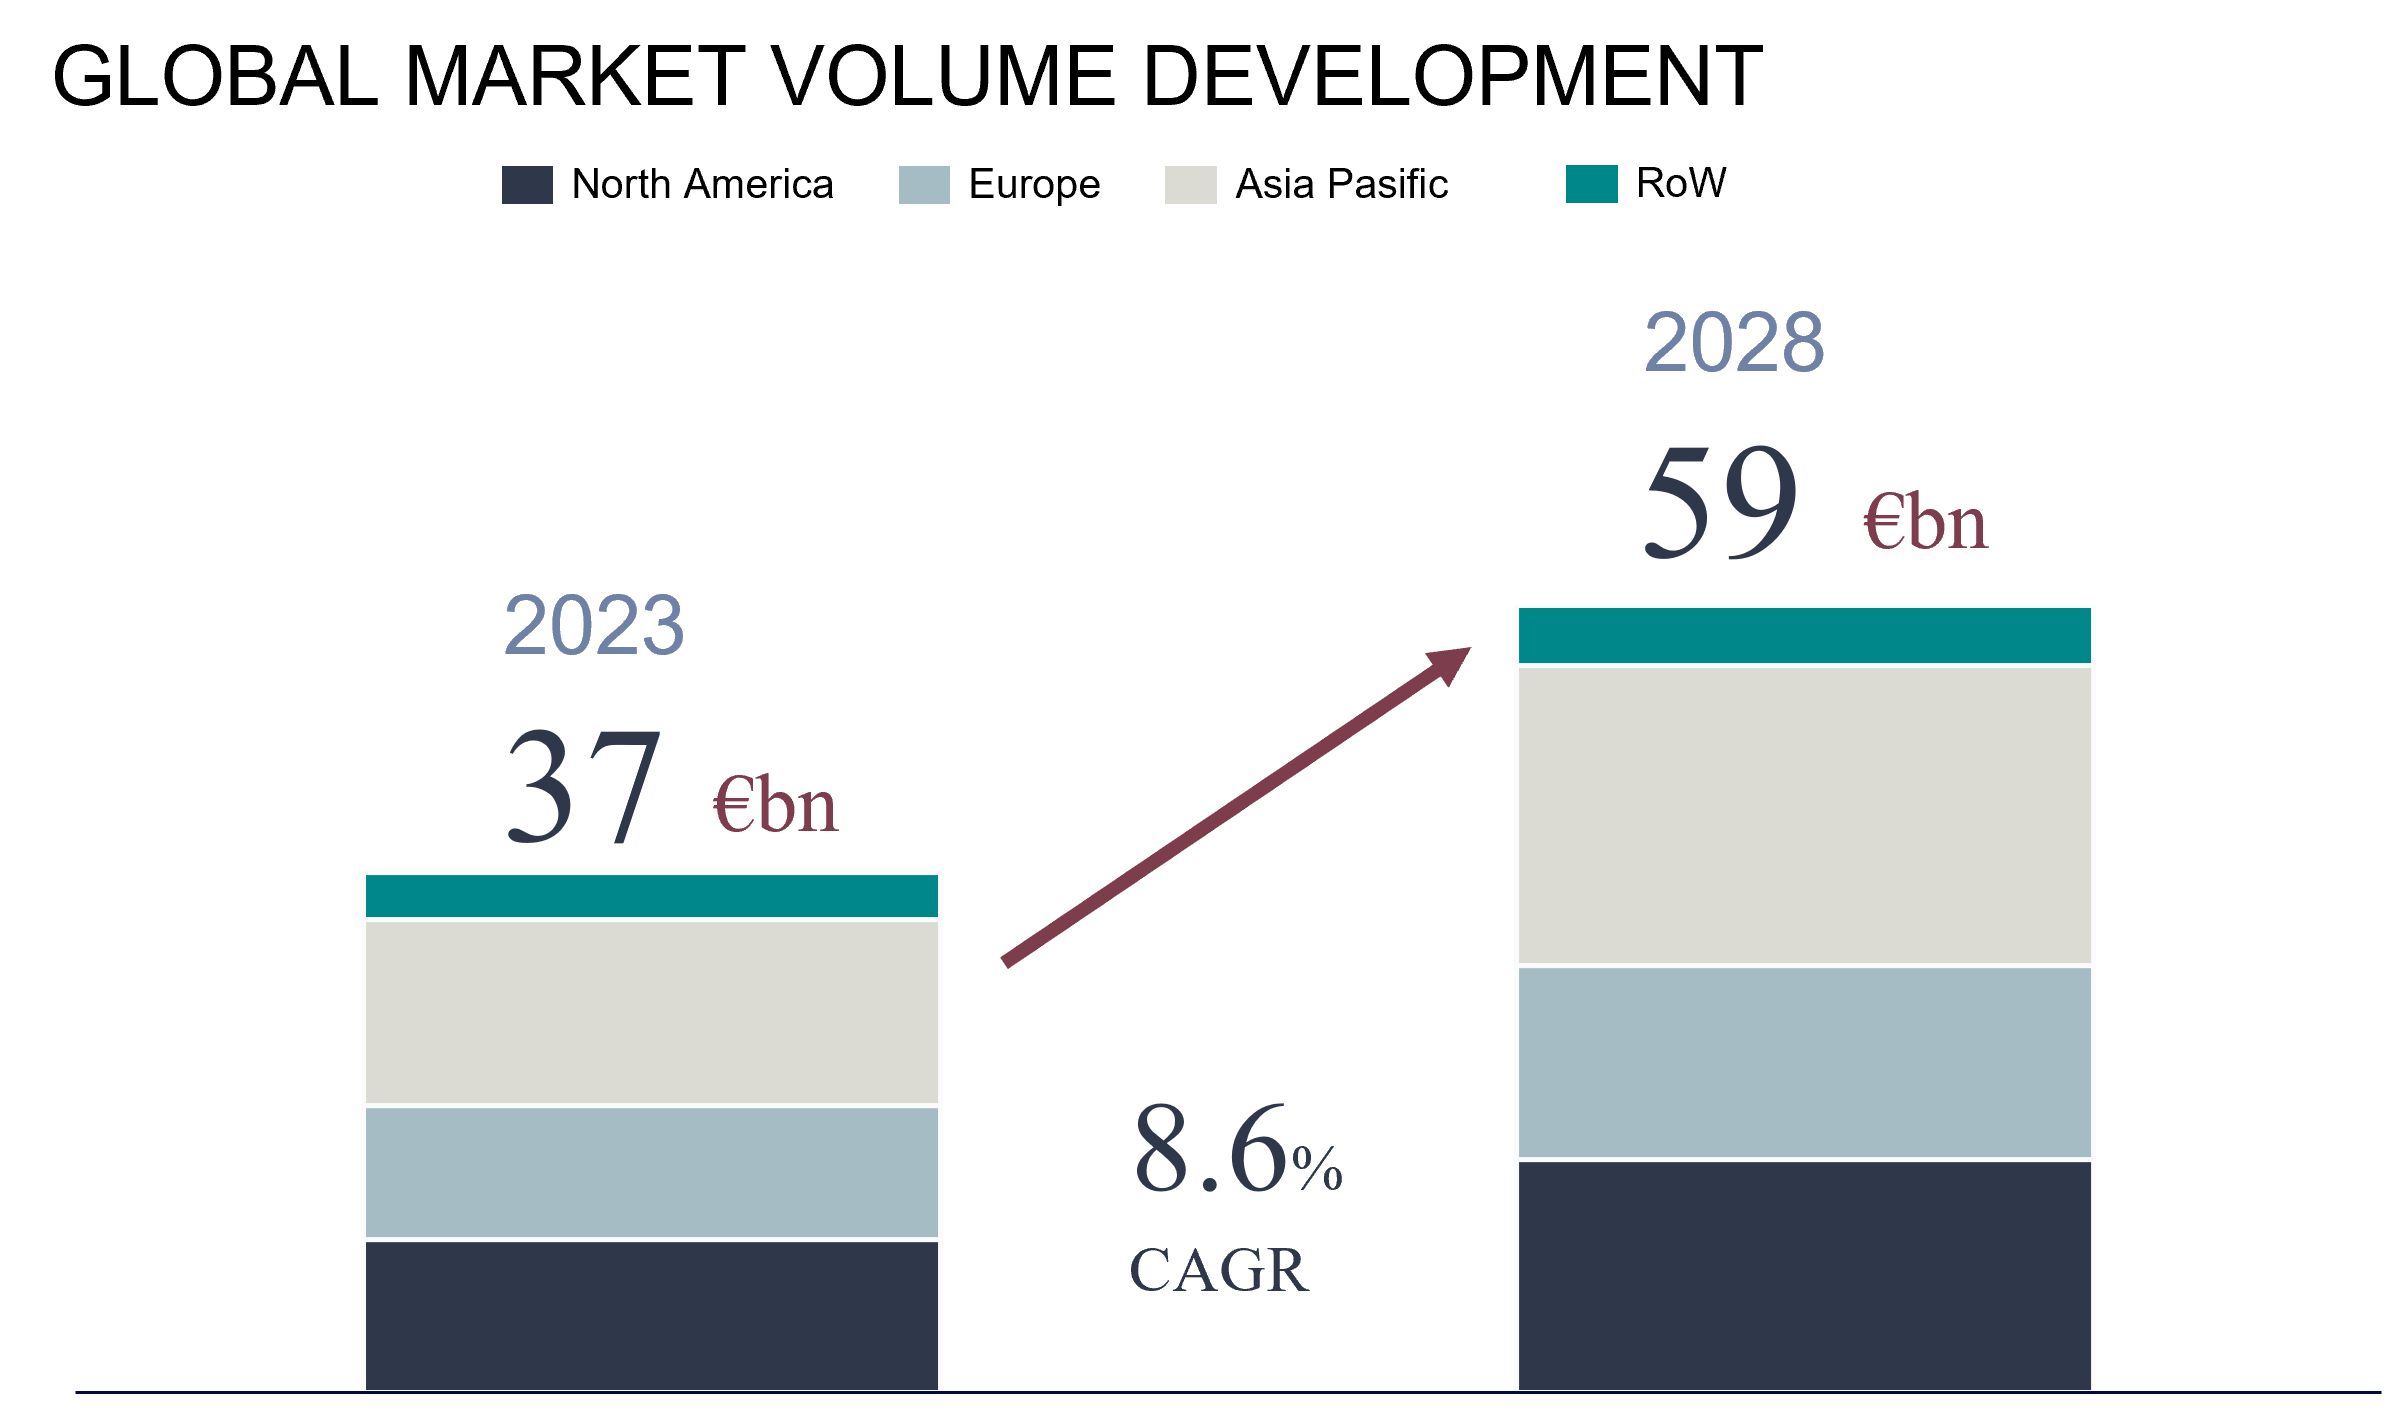
Technologization and Electrification along the full asset lifecycle to increase efficiency in industrial services and processes and comply with CO2 emission regulation.
Industrial Service Valuation drivers
The valuation of industrial services is primarily influenced by three pivotal factors. An increased involvement in the asset lifecycle and the ability to manage complex assets significantly enhance valuation metrics. Moreover, the intricacy of the service offered, and the dynamics of the target market further underpin these valuations. There is a notable shift towards a more comprehensive degree of asset stewardship, ranging from deploying personnel capable of operating the assets on-site to achieving full autonomy in asset management, thereby enhancing and operating the assets entirely independently from the end-user. Specifically, sectors such as energy and chemicals necessitate sophisticated services and assets, due to their inherent complexity and the critical nature of their operations.
Investec has extensive experience in advising deals in the Industrial Service sector. With 25 focused dealmakers across Europe, we can help you to achieve your strategic ambitions.
Interview
As we enter 2024, the M&A landscape shows signs of recovery, albeit cautiously.
In the episode of the February 20, 2024 of No Ordinary Wednesday, Jeremy Maggs in conversation with Investec experts Jürgen Schwarz, Marleen Vermeer, and Kilian de Gourcuff, Investec’s Head of Cross-Border Finance and International Advisory Charles Barlow, on what key sectors, trends and risks to keep an eye on in 2024.
Click below to listen to the podcast:
Where does opportunity lie for dealmaking in 2024? (investec.com)
Hosted by seasoned broadcaster, Jeremy Maggs, the No Ordinary Wednesday podcast unpacks the latest economic, business and political news in South Africa, with an all-star cast of investment and wealth managers, economists and financial planners from Investec. Listen in every second Wednesday for an in-depth look at what’s moving markets, shaping the economy, and changing the game for your wallet and your business.
Listen to the best of No Ordinary Wednesday: https://www.investec.com/en_za/focus/no-ordinary-wednesday-with-jeremy-maggs.html
European Market
The European IT Services M&A market is surging with consolidation driven by the ongoing digital transformation wave, shifts in managed services, and attention from private equity firms.
2023 has seen and will continue to see a spike in M&A activity as businesses seek digital transformation for market competitiveness. With a projected spending of $380 billion and a 6.6% year-on-year growth, the European IT Services market is set for significant expansion.
Cybersecurity, DevOps, software development, quality assurance, digital transformation, low code, and managed services will take centre stage in upcoming deals.
Dutch Market
Private Equity is driving consolidation in the booming Dutch IT Services market, with 25+ platform companies in the digital transformation/managed services sector. Below an overview of Buy & Build platforms in the Netherlands.
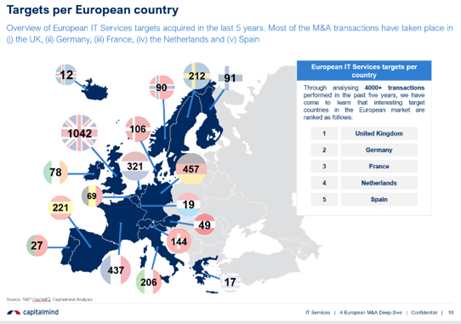
The Netherlands ranks fourth in Europe for IT Services transactions, trailing the United Kingdom, Germany, and France. Our research highlights a notable rise in financially-backed strategic buyers, increasing from ~30% in 2018 to ~40% in 2022.
For more information and our full IT Services 2023 report, please contact Ron Belt or Maurits Odekerken
Embracing innovation and sustainability: the future of the TIC industry
As long-term advisers to the TIC sector, Investec | Investec hosted our inaugural European TIC conference in March 2023. Industry leaders joined us for a lively discussion about the future of the sector – including digitalisation, sustainability, and M&A strategy.
Watch and read the highlights from our inaugural European TIC conference
The Testing, Inspection & Certification (TIC) sector has long played a pivotal role in providing quality and safety control services to protect people, and the environment we live in. Now, several transformative trends are driving further opportunities in the sector.
To help facilitate discussion on these trends, Investec | Investec hosted our inaugural TIC conference on 9 March 2023. Paul Hesselink – CEO Kiwa; Hervé Montjotin – CEO Socotec; and Mark Williams – Partner Inflexion; joined us to provide their views on the sector’s changing dynamics.
Continued M&A activity from both private equity and trade consolidators has seen valuation multiples increase significantly over the last 5 years. The ongoing attractiveness for investors has been underpinned by the strengthening regulatory landscape across a variety of sectors, alongside specific growth drivers within several individual sub-sectors.
We have continued to see buy-and-build strategies play an important role in driving growth, as incumbent players seek to leverage the benefits of scale to address a broad range of sub-sectors and unlock further synergies.
Three common themes repeatedly were raised as the future of the TIC industry was discussed.
Independent verification for ESG
The sector is heavily intertwined with the growing requirement for greater environmental, social, and governance (ESG) standards among businesses. As companies increasingly seek to promote their ESG credentials, avoid accusations of greenwashing and meet incoming European regulations, the TIC sector will play a crucial role, not only in verifying ESG standards, but also in providing guidance to help companies navigate these often-complex issues.
Hervé Montjotin affirmed the growing demand for independent verification, saying, “Regarding sustainability, people need to be reassured by a trusted third party so we can add a lot of value and help avoid greenwashing.”
Mark Williams highlighted the need to test for unforeseen consequences as businesses seek to improve the sustainability of products. He said, “we are using different materials to make things better and more efficient, but these need to be checked to ensure that whatever has been created is more sustainable and that we don’t find out in 15 years that there are negative impacts.”
Paul Hesselink noted that TIC firms are not only ensuring sustainability and ESG compliance for their clients, but are measuring their own performance against these objectives too: “Carbon dioxide footprinting, gender diversity indices…we don’t just measure these for our customers but for our own business too – walking the talk and demonstrating that we are living up to what we preach.”
The digitalisation challenge
As with many industries, the digitalisation trend – which encompasses digital, data and new technologies (notably sensors, portable instruments and the Internet of Things) – is transforming internal processes for the TIC sector, as well as its business models and the services it offers. Our panel acknowledged how influential digital tools have been in liberating productivity and improving profitability.
However, they cautioned that the pace of potential digital disruption is being slowed by the sector’s conservatism, as well as regulatory reticence. For example, regulators still require in-person inspections rather than using digital tools. The panel agreed that the industry should stay one step ahead of the main pack in terms of technology so that it will be ready when its customers and the regulators are, but acknowledged the sector is unlikely to be a change leader.
Expansion in a rising interest rate environment
It was widely accepted that the current economic environment is creating a new set of challenges – particularly in terms of M&A. Mark Williams pointed out that higher borrowing costs could inhibit some forms of M&A activity, but notes that “there is still demand for quality platforms and there are still entrepreneurs that want to sell.” He added that the focus on high margins was particularly important for many private equity buyers.
Paul Hesselink joked that higher interest rates should help shake off the private equity competition, remarking that “industrial and private equity buyers have different dynamics – industrial buyers can be less margin driven as they have more time to develop a business if it is the right cultural fit.”
Hervé Montjotin added that his business had sought a more global expansion strategy as this can help alleviate cyclical risks. He said that while the industry is “cyclical, those cycles are often domestically orientated, and having a global balance can help mitigate such risks.”
Finally, Mark Williams summarised why the TIC space continues to remain an attractive M&A prospect, saying, “We’ve seen the sector evolve and maintain a steady cadence of growth; while the themes have changed, the concept of securing peoples’ lives and futures is the same as it was 50 years ago. Therefore the industry will keep surviving as we need to secure the world around us.”
Download our presentation
Register your interest for next year’s event by contacting Marleen Vermeer